
All three real estate investment trusts (REITs) reporting this week spent the past year reshaping their portfolios.
However, only some of that work has reached unitholders.
Keppel REIT (SGX: K71U), Starhill Global REIT (SGX: P40U) and Lendlease Global Commercial REIT (SGX: JYEU) report between 28 and 30 October 2026.
Two of them went shopping for assets.
The third mostly sat tight.
Here’s the thing: a bigger portfolio does not always mean a bigger payout for you.
| Company | Ticker | Reporting date |
|---|---|---|
| Keppel REIT | SGX: K71U | Wednesday, 28 October 2026 |
| Starhill Global REIT | SGX: P40U | Thursday, 29 October 2026 |
| Lendlease Global Commercial REIT | SGX: JYEU | Friday, 30 October 2026 |
Keppel REIT: Will a bigger portfolio start paying more per unit?
Keppel REIT owns 14 prime commercial assets across Singapore, Australia, South Korea and Japan, with assets under management (AUM) of S$11.8 billion as at 30 June 2026.
Keppel REIT’s purchases lifted its first-half 2026 (1H2026) numbers.
It bought a 75% interest in Top Ryde City Shopping Centre in December 2025 and took a further one-third stake in Marina Bay Financial Centre Tower 3.
Property income rose 16.7% year on year (YoY) to S$159.3 million, while distributable income expanded 22.8% to S$129.6 million.
Unitholders did not see the benefit.
Distribution per unit (DPU) fell 4.0% YoY to S$0.0261 because an enlarged unit base diluted the gains.
In other words, the pie grew, but each slice got smaller.
The buildings themselves remain well let.
Committed portfolio occupancy stood at a healthy 96.0%, accompanied by a positive rental reversion of 12.8%, meaning new and renewed leases were signed at higher rental rates.
North Asia is the soft patch.
Attributable net property income (NPI) from the region fell 12.0%YoY, while Singapore and Australia grew 23.5% and 21.2%, respectively.
So what should you watch on 28 October?
Start with KR Ginza II.
The manager previously agreed to sell the Tokyo building for JPY 11.52 billion (28.4% above its 2022 purchase cost), with completion expected in the third quarter of 2026.
Check whether it has closed.
If the REIT pays out any gain, keep that sum separate from ordinary DPU.
On debt, aggregate leverage stood at 40.0%, with a weighted average cost of debt of 3.27% per annum.
Starhill Global REIT: Can new luxury tenants restart Wisma Atria’s sales?
Starhill Global REIT, or SGREIT, owns nine predominantly retail properties across six Asia-Pacific cities, with a total portfolio valuation of around S$2.7 billion as at 30 June 2026.
SGREIT is the quiet one of the trio.
For its fiscal year ended 30 June 2026 (FY2025/2026), NPI rose 0.1% YoY to S$150.3 million, while DPU rose 0.8% to S$0.0368.
Committed portfolio occupancy improved to 97.2% from 94.6% a year earlier.
Gearing stood at 35.8%, with around 80% of debt on fixed or hedged rates.
Wisma Atria is the property to watch.
Tenant sales there fell 3.7% YoY, which the manager attributed to downtime at the Level 2 façade units ahead of new luxury tenants.
Watch whether those tenants have opened and sales have turned.
Currency is another swing factor.
A stronger ringgit and Australian dollar helped lift SGREIT’s FY2025/2026 results.
A reversal would work against the REIT.
SGREIT also did not disclose rental reversion last period, so any update would reveal its pricing power.
Lendlease Global Commercial REIT: How much growth is left once PLQ Mall is in the base?
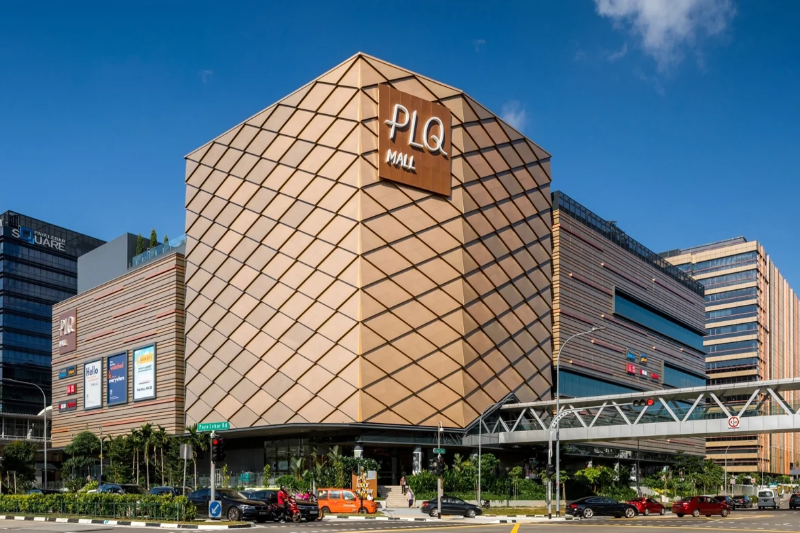
Lendlease Global Commercial REIT, or LREIT, owns Jem, 313@somerset and PLQ Mall in Singapore, plus three Grade A commercial buildings in Milan.
LREIT sold Jem’s office component and bought PLQ Mall in two tranches, completed in November 2025 and March 2026.
For the fiscal year ended 30 June 2026 (FY2026), NPI rose 2.7% YoY to S$152.7 million.
Distributable income jumped 26.0% to S$110.3 million, aided by lower interest expenses and reduced perpetual securities distributions.
Full-year DPU grew at a more modest 3.0% to S$0.037.
PLQ Mall flatters the headline numbers.
Shopper traffic grew 16.4% YoY and tenant sales rose 24.0% across LREIT’s Singapore retail portfolio.
Strip out PLQ Mall, and those increases shrink to 5.2% and 4.0%.
Those are the numbers to track.
LREIT’s committed occupancy slipped to 94.6% from 95.3% a quarter earlier.
Retail occupancy stood at 98.5%, while office occupancy lagged at 89.1%.
On a positive note, LREIT has strengthened its balance sheet.
Gearing fell to 38.9% from 42.6% a year earlier, and the cost of debt dropped to 2.75% per annum.
Watch, too, for news on the 313@somerset event space, due in the second half of 2026.
Get Smart: Follow the growth down to your units
When a REIT grows through acquisitions, compare its distributable income growth with its DPU growth.
The gap tells you how much of that expansion you actually own.
Keppel REIT and LREIT both opened up a wide gap in their latest reporting periods.
SGREIT’s NPI barely grew, yet its DPU still rose.
So when these three report later this week, ask each one the same question: is the growth finally reaching your units?
2008. 2020. 2022. Three of the toughest stretches for Singapore markets in a generation. We found 6 SGX companies that paid a dividend every single year through all three. Our free report reveals the six companies and what allowed them to keep paying when others couldn’t. Click here to download now.
Follow us on Facebook, Instagram, Telegram and YouTube for the latest investing news and analyses!
Disclosure: The Smart Investor does not own units of any REITs mentioned.