Genting Singapore Limited (SGX: G13) has long attracted income investors with its sizeable dividend payouts and attractive yield.
However, is the company’s dividend payout sustainable as it continues to invest in Resorts World Sentosa?
In this article, we take a closer look at Genting Singapore and see if its recent financial performance and cash flow can support its dividend payout.
Why Genting Singapore’s Earnings Have Been Under Pressure
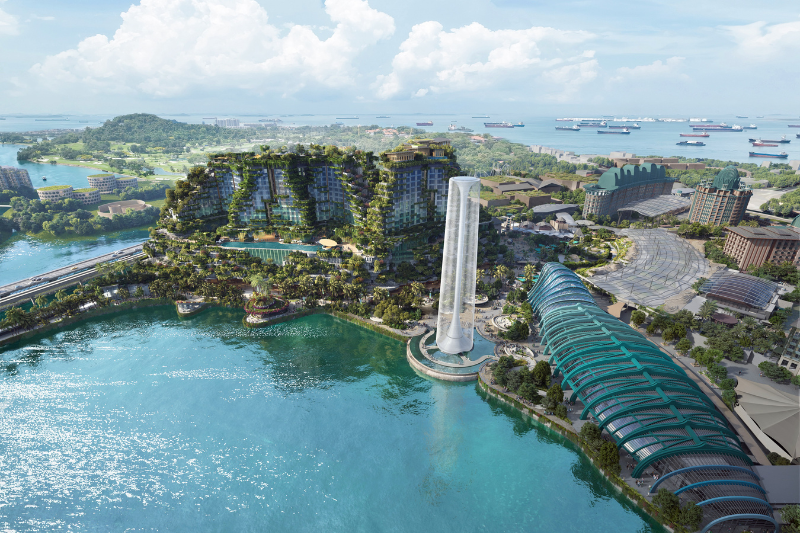
Genting Singapore owns and operates Resorts World Sentosa (RWS), which forms the main focus of its business. Other than RWS’s casino operations, the tourism landmark also offers hotels, attractions such as Universal Studios Singapore, and retail outlets.
The picture is a little different across Genting Singapore’s two main businesses.
Gaming revenue was lower in 1H2026, while non-gaming revenue continued to grow.
Total revenue was broadly unchanged at S$1.2 billion.
Adjusted EBITDA was S$389.8 million, and net profit was S$156.1 million for the six months.
Free Cash Flow Is the Bigger Dividend Question
For income investors, free cash flow is worth watching alongside earnings.
Genting Singapore had S$2.9 billion in cash and cash equivalents as at 30 June 2026.
However, the company continues to spend on RWS.
Its RWS 2.0 transformation involves refreshing existing facilities and developing new offerings, with significant cash outflows during 1H2026.
The company said it remains focused on prudent capital management as it continues to reinvest in RWS.
For Genting Singapore, the amount of cash left after capital expenditure will therefore be important for its dividend.
Earnings Payout Ratio
Genting Singapore declared an interim dividend of S$0.02 per share for 1H2026.
EPS for the period was S$0.0129.
On that basis, the interim dividend was higher than the earnings generated for the period.
The company does have a sizeable cash balance of S$2.9 billion, which gives it some room to continue paying dividends while it spends on RWS 2.0.
Balance Sheet
Genting Singapore’s balance sheet remains in a relatively strong position.
As at 30 June 2026, the company had S$2.9 billion in cash and cash equivalents, while total equity stood at S$8.1 billion.
Its strong cash position gives Genting Singapore some financial flexibility as it continues to invest in RWS and pay dividends.
Capital Requirements
The main thing I would watch here is RWS 2.0.
Genting Singapore has approved a total investment of about S$6.8 billion for the RWS 2.0 transformation of Resorts World Sentosa, of which about S$4.5 billion was committed under its agreement with Sentosa Development Corporation.
As at 30 June 2026, it also had about S$2.95 billion of contracted capital expenditure for property, plant and equipment.
This could be a key factor that may affect how much cash the company has available for dividends in the coming years.
What Could Make Genting Singapore a Better Dividend Stock?
A stronger tourism recovery would be positive for Genting Singapore.
More international visitors could support gaming, hotels and attractions at Resorts World Sentosa.
The RWS 2.0 investments could also support the business as new and upgraded facilities come on stream.
The wider Greater Sentosa Master Plan could add to the area’s appeal over the longer term, although its developments are expected to come on stream from the early 2030s.
For me, the key is whether these investments lead to stronger earnings and cash flow.
That would give the company more room to maintain its ordinary dividend and potentially return more cash to shareholders.
What Could Threaten the Dividend?
Genting Singapore’s dividend still faces some risks.
Gaming revenue can be affected by changes in consumer spending, while a weaker tourism environment could affect gaming, hotels and attractions at RWS.
The company is also spending heavily on RWS 2.0.
If capital expenditure remains high, there could be less cash available for dividends.
Is Genting Singapore a Dividend Grower or a Dividend Payer?
I see Genting Singapore more as a dividend payer than a dividend grower at this stage.
The company has a track record of returning cash to shareholders, but the size of its dividend can vary depending on earnings and capital requirements.
With RWS 2.0 still requiring significant investment, I would be more interested in whether Genting Singapore can maintain its dividend while continuing to fund the business.
A sustained increase in earnings and cash flow would give the company more room to grow its dividend over time.
How Does Genting Singapore Compare With Other Singapore Income Stocks?
Compared with banks such as DBS Group Holdings Limited (SGX: D05) and OCBC Limited (SGX: O39), Genting Singapore offers a different income proposition.
Its earnings are more closely linked to tourism and gaming activity, so its dividend can be more affected by business cycles.
Real estate investment trusts (REITs) and banks are also common choices for income investors, but Genting Singapore gives investors exposure to an operating business rather than a property portfolio.
Investors should also look at its valuation and dividend yield against historical levels before deciding if the stock still offers good value.
Get Smart: A Better Dividend Stock Needs More Than a High Yield
Genting Singapore continues to pay a sizeable dividend, but there are other things investors should look at as well.
Its cash balance remains strong, although the company is still spending on RWS 2.0.
For me, the key question is not just how much dividend it pays, but whether the business can continue to support those payouts.
If earnings and cash flow improve, Genting Singapore could become a better dividend stock over time.
Imagine a life where steady income flows, no matter the market. Our new free report, “Retire Early with Dividends,” reveals how. We’ve pinpointed 5 dependable Singapore dividend stocks that offer a proven, stress-free path to financial freedom. Stop just dreaming and start building your early retirement plan today. Your free guide awaits here.
Follow us on Facebook, Instagram, Telegram and YouTube for the latest investing news and analyses!
Disclosure: Darien C. does not own shares of any companies mentioned.