Three S-REITs outside the typical blue-chip names are handing unitholders higher distributions per unit (DPU) this September.
All three managed year-on-year DPU growth for the first half of 2026 (1H2026).
A rising DPU is the reward.
Whether it can repeat is the question that counts.
OUE REIT (SGX: TS0U)
OUE REIT is a diversified landlord with six office, hospitality, and retail properties in Singapore, as well as a commercial asset in Sydney.
Unitholders received their distributions on 3 September 2026.
DPU surged 28.6% year on year (YoY) to S$0.0126 for 1H2026 – a growth rate that comfortably outpaced the other names in this list.
A strong rebound in hospitality led the charge, with segment net property income (NPI) rising 12.3% to S$45.1 million as revenue per available room (RevPAR) climbed 10.7% to S$258.
At the same time, finance costs dropped 16.6% to S$37.8 million, and joint venture contributions swelled 30.6% to S$8.2 million.
The addition of a 19.9% stake in Sydney’s Salesforce Tower on 16 March 2026 chipped in S$2.2 million via share of associate results.
Looking at core operations, Singapore office occupancy dipped slightly to 91.5% (down 3.7 percentage points quarter on quarter), while Mandarin Gallery held a 94.7% occupancy rate with a positive rental reversion of 5.6% for 2Q2026.
The Sydney property remained fully leased.
Aggregate leverage ended the period at 41.5%.
Looking ahead, the manager proposed divesting Crowne Plaza Changi Airport on 25 June 2026 for S$500 million.
If unitholders approve the sale, it could trigger a separate special distribution of S$20.0 million on top of regular operational distributions.
Sasseur REIT (SGX: CRPU)
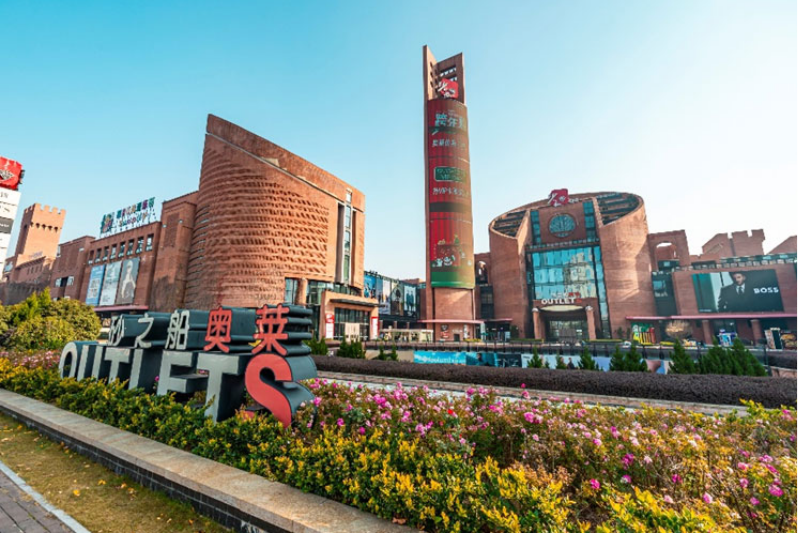
Sasseur REIT owns four outlet mall properties across Chongqing, Hefei, and Kunming in China.
Unitholders can expect their 1H2026 distribution on 24 September 2026.
DPU rose 10.2% YoY to S$0.03366, even after the manager decided to retain 10% of distributable income.
Driving this jump was a record first-half outlet sales performance of RMB 2.3 billion – up 7.4% YoY – alongside a 20.7% surge in footfall to 9.8 million visitors.
Unlike most peers, Sasseur REIT operates on an Entrusted Management Agreement (EMA) structure rather than collecting traditional NPI.
Under this arrangement, EMA rental income climbed 4.3% YoY to RMB 350.7 million.
In Singapore dollar terms, that translated to a 6.8% increase to S$65.4 million, benefiting from a stronger RMB against the Singapore dollar.
Its balance sheet remains exceptionally lean.
Aggregate leverage stood at just 25.6%, giving it S$865 million in debt headroom – one of the lowest gearing ratios among S-REITs.
Weighted average cost of debt dropped to a record low of 3.7% (down from 4.4% at the end of 2025), and the manager successfully extended its onshore loan tenor out to 2031.
With all borrowings denominated in RMB, the REIT enjoys a natural currency hedge.
On the operational side, portfolio occupancy remained healthy at 97.2%, though rental reversion figures were not disclosed.
Over at the Hefei outlet, the manager is busy repurposing a former cinema space, where 11 out of 13 new units are already pre-committed.
A broader brand clustering initiative is set to roll out from 3Q2026.
United Hampshire US REIT (SGX: ODBU)
United Hampshire US REIT, or UHREIT, holds a portfolio of 21 grocery-anchored and necessity-based retail properties alongside two self-storage facilities in the United States.
Payout date for unitholders is set for 28 September 2026.
DPU rose 3.4% YoY to US$0.0216 for 1H2026.
Distributable income actually expanded at a faster pace of 5.8% to US$13.7 million, with the slight dilution coming from an expanded unit base.
Total units in issue grew to 608.2 million as at 30 June 2026, up from 596.9 million a year prior, driven by issuances under the distribution reinvestment plan and payment of manager performance fees.
NPI ticked up 6.4% YoY to US$25.5 million, while gross revenue expanded 5.8% to US$37.8 million.
Occupancy across the grocery and necessity assets came in at a solid 97.6%, while self-storage occupancy surged 430 basis points to 93.5%.
The manager retained 90% of expiring tenants and signed over 260,000 square feet of new and renewal leases during the period.
Growth was driven by fresh leases, built-in rent escalations, and new contributions from Dover Marketplace and Wallingford Fair.
The latter was acquired in Connecticut in January 2026 for US$21.4 million – an 8.2% discount to its independent valuation.
Note that UHREIT reports and distributes its payouts entirely in US dollars.
Get Smart: Look Beyond the Headline Percentage
A headline DPU increase is always nice to see, but the source of that growth matters just as much as the number itself.
Payout growth supported by organic tenant sales and lower borrowing costs is far more sustainable than a bump driven by a one-off asset deal or temporary tailwind.
If you own or are considering any S-REIT paying a higher DPU, look past the headline number.
Identify what produced it, and ask whether those drivers can deliver again.
You walk past million-dollar opportunities every single day. Your coffee shop. Your commute. Your grocery run. But these “boring” Singapore companies are quietly building fortunes while everyone chases crypto and overpriced tech stocks. Our latest report reveals 5 small-cap goldmines hiding in plain sight. Click here to download for free now before prices catch up.
Follow us on Facebook, Instagram, Telegram and YouTube for the latest investing news and analyses!
Disclosure: Calvina L. does not own units of any REITs mentioned. Chin Hui Leong contributed to this article and does not own units of any REITs mentioned.