

A strong Singapore dollar against the Malaysian ringgit has long driven Singaporean consumers up north for necessities.
The completion of the Johor Bahru (JB)–Singapore Rapid Transit System (RTS) Link gives them more reasons to do so, resulting in a projected net S$290 million of outbound consumer spending in JB.
While JB businesses are expected to benefit, some Singaporean businesses could see growth derailed.
Crucially, the retail leakage is geographically and sectorally uneven, affecting real estate investment trusts (REITs) in the non-central region and other businesses providing essential services.
Frasers Centrepoint Trust (SGX: J69U), or FCT – Suburban Landlord Taking a Direct Hit From RTS
With around half of FCT’s retail portfolio providing essential services, it’s arguably one of the hardest-hit REITs from increased cross-border convenience.
In the first half ended 31 March 2026 (1HFY2026), FCT’s revenue increased 20.3% to S$221.9 million, driving net property income up 20.2% to S$160.8 million year on year (YoY).
Aside from higher rents collected across most malls, its latest growth was also supported by the acquisition of Northpoint City South Wing.
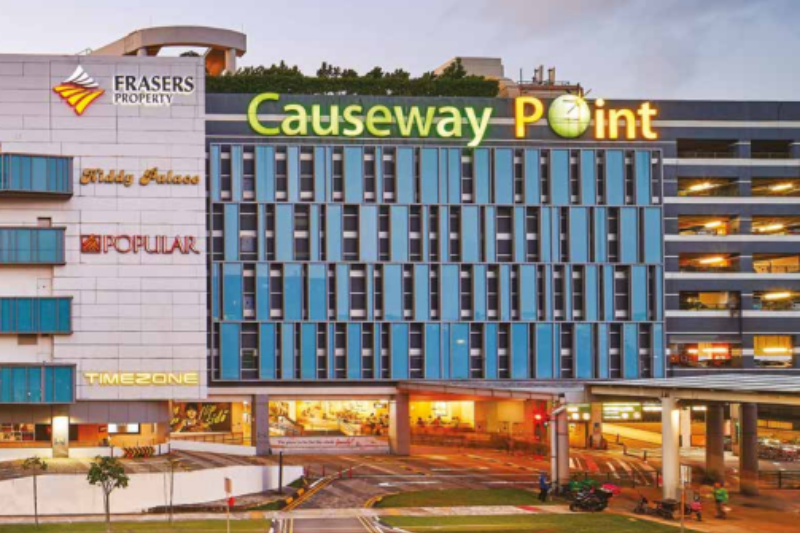
Crucially, Causeway Point, FCT’s largest mall by property value, is located at Woodlands MRT station, right next to Woodlands North station, where the JB-Singapore RTS terminal is located.
The implications?
If nearby residents can get comparable retail therapy services at lower costs with just a few minutes’ ride to JB, why would they choose to spend at Causeway Point?
To make things worse, this price arbitrage opportunity could also appeal to consumers from nearby suburban malls like Northpoint City (another property of FCT).
Sheng Siong (SGX: OV8) – Defensive Business Anchored by Fresh Produce and Government Vouchers
Renowned for its operational efficiencies, Sheng Siong now sees its 90 outlets across Singapore’s HDB estates face a potential retail outflow as value hunters head north for their grocery fixes.
It doesn’t help that its footprint extends across heartland areas, which mostly include non-central regions that are vulnerable to the impact of consumer loss to JB.
However, it helps that the supermarket operator’s revenue mix includes fresh produce like raw seafood, meat, fruits, and vegetables, which face strict customs restrictions.
For the six months ended 30 June 2026 (1HFY2026), its revenue increased 11.9% YoY to S$855.4 million.
Aside from higher sales from newly opened stores and promotional discounts, purchases from Community Development Council (CDC) vouchers also contributed materially to its revenue growth, making these vouchers a potential trump card for Singaporean supermarket businesses like Sheng Siong.
Despite rising business operation costs, its 1HFY2026 gross profit grew 15.6% YoY to S$272.4 million as Sheng Siong improved its sales mix – a sign that the management is capable of adapting to the impending headwinds of improved cross-border travel.
DFI Retail Group (SGX: D01) – Regional Diversification Could Cushion the Localised Singapore Headwinds
Despite DFI’s revenue dipping 6% to US$4.14 billion YoY following the divestment of its Singapore Food business (Cold Storage and Giant), its underlying profit for the six months ended 30 June 2026 (1H2026) surged 11% to US$117 million, thanks to sales recovery of existing divisions and effective cost optimisation measures.
The divestment announced in March 2025 saw the group selling Cold Storage and Giant for S$125 million, effectively removing much of the risk related to direct grocery price arbitrage.
With this divestment, 7-Eleven and Guardian anchor DFI’s Singapore presence in the convenience and drugstore sectors, respectively.
While 7-Eleven provides proximity conveniences that Singaporean consumers cannot get from JB, Guardian, DFI’s local health and beauty retail chain, is particularly vulnerable.
This vulnerability is due to competition from the steep price discounts of JB “drugstores”, which contribute to the second-highest share of Singaporeans’ spending in JB.
Still, the impact on DFI could be muted.
This is because while Guardian’s Singapore outlets face headwinds from increased cross-border commuting, its regional pharmaceutical footprint through brands such as Mannings in Hong Kong and Guardian across Southeast Asia could potentially cushion the impacts – something for investors to monitor.
Get Smart: Distinguish the Resilient from the At-Risk
As the RTS Link drives a structural shift in consumer behaviour that permanently shapes the Singapore retail landscape, the defensive stability of providing essential services to heartland consumers can no longer be taken for granted.
FCT, previously lauded as a defensive heartland landlord, could see its rental reversion take a beating, while regionally diversified players like DFI Retail Group could be cushioned from the impact.
The impact on local grocery operators like Sheng Siong could be muted, as fresh produce and CDC vouchers provide credible moats to defend the heartland supermarket operator’s margins.
Amid the inevitable headwinds as the easing of cross-border travel siphons away local value-hunting consumers, smart investors should lean towards businesses with meaningful regional diversification and a resilient product mix.
You’ve probably shopped at their malls, banked with them, or bought their products this month. These 6 SGX companies have paid dividends for 20 straight years, GFC and COVID included. Our FREE report shows you which ones, and what has kept their dividends going for 20 years and more. Grab your copy here.
Follow us on Facebook, Instagram, Telegram and YouTube for the latest investing news and analyses!
Disclosure: Larry L. owns units of FCT.


