

Earnings season is when real estate investment trust (REIT) investors find out whether rents kept pace with borrowing costs.
Not every Singapore REIT passed that test this time round.
Three did, and raised their distribution per unit (DPU) in the process.
The three REITs report over different periods.
Compare the direction of each trend, not the size of the numbers.
Can Frasers Centrepoint Trust keep raising its payout?
Frasers Centrepoint Trust (SGX: J69U), or FCT, is Singapore’s largest suburban retail mall owner.
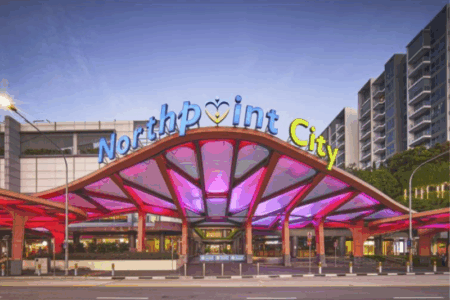
Its eight malls include Northpoint City, Causeway Point and Waterway Point.
For the fiscal year ended 30 September 2026 (FY2026), gross revenue rose 14.2% year on year (YoY) to S$444.9 million.
Net property income (NPI) grew 15.7% to S$321.7 million.
DPU climbed 2.0% YoY to a record S$0.1235.
NPI grew far faster than DPU.
Northpoint City South Wing, which FCT bought in May 2025, contributed for a full year and accounts for most of the NPI increase.
Distributions from joint ventures fell 11.7% YoY because a one-off special dividend did not recur.
The malls themselves are in good shape.
Retail committed occupancy stood at 99.7% as at 30 September 2026.
This excludes the divested White Sands and NEX, which is undergoing an asset enhancement initiative (AEI).
Rental reversion for FY2026 came in at 6.6%.
FCT is also borrowing more cheaply.
Its average cost of debt fell to 3.2% from 3.8% a year ago.
FCT sold White Sands on 30 September 2026 and will use the proceeds to repay borrowings.
That will cut aggregate leverage from 38.7% to 36.8%.
The thing to watch is the AEI pipeline.
NEX’s first-phase upgrade is 98% pre-committed and due to finish in December 2026.
Causeway Point’s AEI is due to start in the second quarter of 2027.
Upgrades take space offline while work is under way, and that can slow income growth for a while.
The payoff can be worth it.
The completed Hougang Mall AEI delivered a return on investment of about 8%.
Is Keppel DC REIT’s growth worth the extra debt?
Keppel DC REIT (SGX: AJBU) owns 27 data centres across 10 countries, with Singapore and Japan being its two largest markets.
For the first nine months of 2026 (9M2026), gross revenue rose 13.3% YoY to S$365.3 million.
NPI increased 13.1% to S$316.8 million.
DPU grew 11.7% YoY to S$0.0857.
Positive rental reversions and escalations lifted NPI.
Rental reversion averaged around 14% for 9M2026, and portfolio occupancy improved to 93.0% from 92.5% in 2Q2026.
Tokyo Data Centre 3 added to NPI, while larger stakes in Keppel DC Singapore 3 and 4 meant more of that income flowed to unitholders.
On the flip side, Keppel DC REIT lost income from Kelsterbach Data Centre, sold in March 2025, and from Cardiff Data Centre, where the client’s contract expired in June 2026.
Finance costs rose 28.1% YoY.
There’s a per-unit effect to note too.
A larger unit base after the September 2026 private placement diluted DPU because the new units arrived before the new Tokyo assets started contributing income.
In other words, the 11.7% DPU growth came despite a timing drag that should fade.
That placement funded part of a bigger move.
On 1 October 2026, Keppel DC REIT completed the purchase of an 88.62% effective interest in Tokyo Data Centre 4 and 5 for around S$1.4 billion.
Both assets are fully occupied, and their in-place rents sit more than 30% below market.
Management expects the deal to lift DPU by 2.0%.
The trade-off is leverage.
A S$625 million private placement paid for part of the deal, and yen-denominated debt covered the rest.
Aggregate leverage stood at 36.2% as at 30 September 2026 and rose to 38.8% on a pro forma basis.
Those below-market Tokyo rents are the key: they need to reset higher over time to cover the bigger interest bill.
What’s behind Suntec REIT’s higher DPU?
Suntec REIT (SGX: T82U) owns 10 office, retail and convention properties across Singapore, Australia and the UK.
For the third quarter of 2026 (3Q2026) ended 30 September 2026, gross revenue rose 5.2% YoY to S$123.6 million.
NPI increased 6.2% to S$83.4 million, while DPU climbed 13.4% YoY to S$0.02017.
Keep in mind that these figures cover a single quarter.
DPU grew more than twice as fast as NPI.
Lower financing costs help explain that gap.
Suntec REIT’s Singapore offices and malls drove the quarter.
Committed occupancy for the Singapore office and retail portfolios stood at 99.6% and 98.6% respectively.
Rental reversions came in at 7.3% and 11.2% respectively.
Tenant sales per square foot at Suntec City Mall rose 10% YoY.
Australia is where things get interesting.
Backfilled leases at 177 Pacific Highway and higher occupancy at 477 Collins Street also added to income this quarter.
Suntec REIT now wants to sell both, along with 21 Harris Street.
It has launched sales campaigns for all three to reduce overseas exposure.
For income investors, that cuts both ways.
Selling these buildings would remove some of the income that helped this quarter.
Its aggregate leverage rose to 43.0% as at 30 September 2026, from 41.5% at end-2025.
Management lists lower leverage and unit buy-backs among its capital management options.
Whether DPU holds up from here will depend on the sale prices and where the money goes.
Get Smart: Find out where the DPU growth comes from
A rising DPU is good news, but where the increase comes from matters more.
Growth from higher rents at existing properties can repeat year after year.
Growth from cheaper debt or a newly bought asset deserves a second look.
Interest rates can rise again, and an acquisition only pays off if the REIT didn’t overpay.
All three REITs here raised rents.
FCT and Suntec REIT also borrowed more cheaply.
Keppel DC REIT issued more units and took on more debt to expand in Tokyo.
So the next time a REIT raises its payout, check whether rental reversions are positive and whether leverage is climbing.
When rents are rising and leverage is steady, you’re looking at a distribution with room to grow.
The world’s gotten unpredictable, but some Singapore companies have quietly kept thriving. You’ve probably seen them in your daily life. And yes, they’ve kept paying dividends through it all. Meet 5 resilient stocks built to navigate global storms. Get the free report here and see how they’ve done it.
Follow us on Facebook, Instagram, Telegram and YouTube for the latest investing news and analyses!
Disclosure: The Smart Investor owns units in FCT and Keppel DC REIT.