The Straits Times Index (SGX: ^STI)’s strong year-to-date (YTD) rally of more than 20% has rewarded investors who stayed invested.
After this first wave of gains, investors tend to start hunting for whatever may lead the next leg – and that’s rarely the stocks that have already run the hardest.
The better candidates are businesses whose earnings could accelerate, valuations still leave room to re-rate, or have catalysts that could shift how the market sees them.
Here are three.
What Could Drive the Next Singapore Market Rally?
Lower interest rates could cut financing costs and support valuations for income-generating assets.
Stronger corporate earnings give any rally a more durable foundation than sentiment alone.
Improving investor sentiment could pull more capital into Singapore equities generally.
And, finally, sector rotation, where money is shifted into laggards with better forward prospects, could also fund the next leg up for the market.
That said, momentum alone won’t be enough; the next leaders need real catalysts behind them.
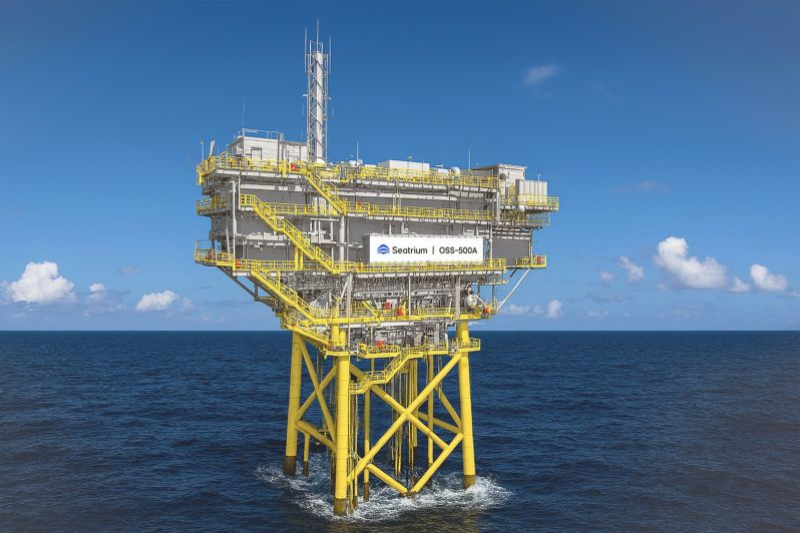
Seatrium Limited (SGX: 5E2) – The Earnings Growth Leader
Seatrium’s latest numbers for the first half of 2026 (1H2026) show genuine business inflection.
Revenue grew a modest 5% year on year (YoY) to S$5.6 billion, but that’s only part of the story: gross profit rose 22% to S$482 million, and gross margin ticked up to 8.6% from 7.4% a year ago.
The strong follow-through to earnings is best seen in Seatrium’s EBITDA surging 60% to S$651 million and net profit (excluding divestment) jumping 54% to S$212 million.
Seatrium’s return on equity (ROE) was also decent at 7.8%.
The company’s future growth looks bright, with a net order book of S$13.3 billion as of 30 June 2026.
Adding new contracts to this order backlog and continuing the decent showing of expanding profit margins could lead to further earnings growth and a higher share price correspondingly.
To cap things off, Seatrium trades at a reasonable forward price-to-earnings (P/E) ratio of 15x, against a historical three-year average of 32x.
UOB Group Holdings (SGX: U11) – The Undervalued Blue Chip
Compared to its local bank peers, DBS (SGX: D05) and OCBC (SGX: O39), UOB’s share price return has trailed.
But UOB currently has a decent valuation with a price-to-book (P/B) ratio of 1.3x, which is the same as the three-year historical average.
Moreover, UOB’s P/B ratio is significantly lower than DBS’ 3.1x and OCBC’s 2.2x.
Despite the valuation discount, UOB has continued to deliver in both earnings and balance sheet strength.
Net profit after tax rose 10% YoY to S$1.5 billion in 1H2026, even though the net interest margin (NIM) declined by 0.17 percentage points to 1.74%.
UOB’s non-performing loans (NPL) ratio is healthy at 1.6%, while it sports a fully phased-in common equity tier 1 (CET1) ratio of 15%.
This affords UOB plenty of room to grow its recent dividend of S$0.88 per share for 1H2026.
Keppel DC REIT (SGX: AJBU) – The Structural Growth Play
Data centre demand tied to AI and cloud computing is about as clean a structural growth trend as exists on the Singapore Exchange (SGX: S68).
Keppel DC REIT, or KDC REIT, is Singapore’s largest pure-play vehicle for it, with 25 data centres across 10 countries.
For 1H2026, KDC REIT’s distributable income grew 18.5% YoY to S$150.7 million, and distribution per unit (DPU) rose 11.3% to S$0.05714.
The portfolio’s rental reversion came in around 10%, through renewals in Singapore and Australia, with the weighted average lease to expiry (WALE) extended to 6.7 years from 6.5 years a quarter ago.
Meanwhile, gearing is low at 34%, which gives real financial flexibility to the REIT to acquire more data centres and strengthen its earnings profile.
What Could Stop the Rally?
A global economic slowdown would hit all three, though unevenly.
Higher-for-longer interest rates would particularly pressure KDC REIT’s valuation and UOB’s re-rating case.
Weakening corporate earnings would undercut Seatrium’s margin story specifically.
Geopolitical uncertainty (already visible in Seatrium’s Middle East-related disruption) is a live risk.
And after a strong run, profit-taking or valuations simply running ahead of fundamentals could stall any of the three regardless of how good the underlying business is.
Should You Buy Before the Next Rally?
Don’t chase what’s already rallied hardest – by definition, less upside remains once expectations are elevated.
Look for earnings before momentum: strong fundamentals are a better foundation than recent price action alone.
Consider staggering purchases rather than deploying all capital at once, since timing any rally precisely is close to impossible.
And keep valuation in perspective – even an excellent business can produce poor returns if bought at too high a price.
What Should Investors Monitor From Here?
For all three: quarterly earnings, management guidance, analyst revisions, and valuation changes relative to history.
For Seatrium specifically: new contract wins against that S$32 billion pipeline, and whether margin gains hold once one-off items roll off.
For UOB: The dividend growth, any signs of re-rating in the P/B multiple, and Greater China credit trends.
For KDC REIT: occupancy (watch the Cardiff vacancy that dented 1H2026’s headline number), further acquisitions, and DPU growth sustaining above its historical mid-single-digit pace.
Get Smart: The Next Winners May Already Be on Your Watchlist
Market rallies create new winners as capital rotates between sectors.
Seatrium, UOB and Keppel DC REIT shouldn’t be judged on how far they’ve already run, but on whether their earnings, cash flows and structural positioning can support another leg higher – and on the evidence so far, all three have a genuine, if different, case.
The next market leader may not be the stock making the most noise today.
It could be the one whose fundamentals are just beginning to catch up with its potential.
If you want to retire with a constant stream of dividends, these 5 stocks might be all you need. We’ve found 5 SG stocks that have kept paying (and growing) through inflation, rate hikes, and recessions. See what they are with our latest free report for SGX dividend investors. Click here to get instant access.
Follow us on Facebook, Instagram, Telegram and YouTube for the latest investing news and analyses!
Disclosure: Wilson H. does not own shares in any of the companies mentioned.