Many Singaporeans rely on their CPF accounts for a safe, steady return, but for those seeking higher yields, the local REIT market offers a compelling alternative.
Currently, the CPF Ordinary Account continues to offer a guaranteed 2.5% interest rate, while the Special, MediSave, and Retirement Accounts provide a steady 4.0%.
While these figures are dependable, top-tier REITs can provide distributions that comfortably outpace these benchmarks.
We look at three resilient players that have recently reported their earnings.
These trusts offer exposure to high-quality retail, office, and industrial assets, delivering yields that make your retirement savings work even harder.
Starhill Global REIT (SGX: P40U) – The Orchard Road Retail Specialist
Starhill Global REIT, or SGREIT, remains a steady hand in the retail space with a portfolio of nine mid- to high-end properties valued at approximately S$2.8 billion.
Its latest 1HFY2025/26 results showcased remarkable stability in a fluctuating market.
Gross revenue held firm year on year (YoY) at S$96.3 million, though net property income (NPI) dipped marginally by 0.8% to S$75.1 million.
This slight decline was primarily due to the divestment of office units at Wisma Atria and rental provisions in China, coupled with a weaker Australian dollar.
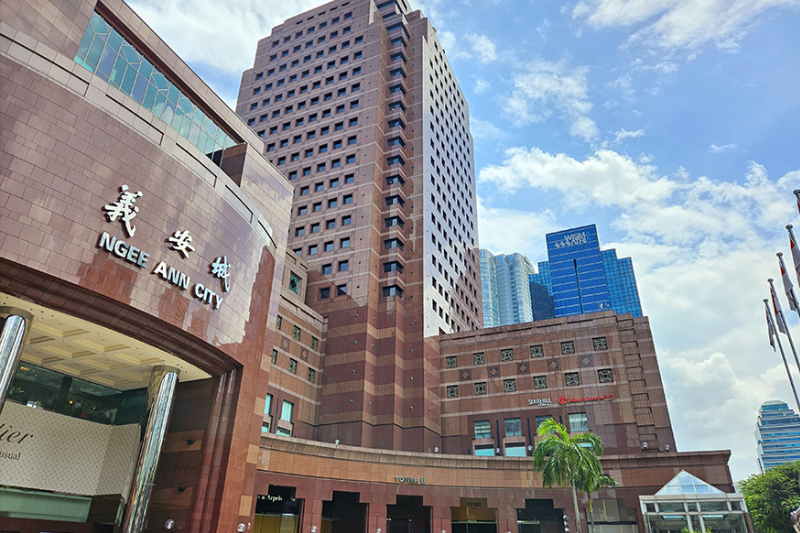
However, these were largely balanced by higher contributions from iconic assets like Ngee Ann City and Lot 10.
Investors should be pleased that the distribution per unit (DPU) remained flat at S$0.018 for the half-year.
Based on its recent unit price of S$0.59, this translates to an attractive annualized distribution yield of approximately 6.1%, significantly higher than the standard CPF Ordinary Account rate.
The trust’s Singapore portfolio is nearly full with 99.6% occupancy, and the recent renewal of the Toshin master lease at Ngee Ann City at a 1.0% higher base rent signals continued demand.
Management is also being proactive with its capital; by issuing S$100 million in new perpetual securities at 3.25% to redeem older 3.85% ones, they are effectively trimming financing costs.
With asset enhancements underway at Myer Centre Adelaide and a new replacement tenant signed for its China property in January 2026, SGREIT is positioning itself to maintain its dependable status.
Mapletree Pan Asia Commercial Trust (SGX: N2IU) – The Diversified Commercial Giant
With S$15.7 billion in assets under management (AUM) across five Asian gateway markets, Mapletree Pan Asia Commercial Trust, or MPACT, is a heavyweight in the commercial sector.
Its third-quarter results for FY2026 (3QFY2026) revealed a nuanced performance that ultimately favored shareholders.
While gross revenue and NPI dipped slightly by 1.9% and 1.2% respectively, DPU actually rose 2.5% YoY to S$0.0205.
At a unit price of S$1.46, this gives the REIT a healthy annualized distribution yield of about 5.6%.
This growth was supported by a 10.2% reduction in finance expenses as the REIT lowered its weighted average cost of debt to 3.20%.
The star of the show remains VivoCity, which maintained full 100% commitment as at 31 December 2025 and recorded a stellar rental reversion of 14.7%.
Shopper traffic and tenant sales at the mall also continued their upward trajectory, up 2.6% and 3.8% YoY respectively, with sales climbing to S$821.0 million.
Conversely, MPACT’s China properties faced significant challenges, with rental reversions sliding by 21.2%.
To mitigate these risks, MPACT is sharpening its focus on Singapore, which currently contributes 58% of the portfolio value.
The proposed S$328.1 million divestment of the Festival Walk office tower is a strategic pivot that will see Singapore’s contribution to NPI rise to 66% once completed in February 2026.
This shift toward the stable home market, combined with disciplined cost management, makes MPACT a robust contender for investors seeking market-beating passive income.
Frasers Logistics & Commercial Trust (SGX: BUOU): The Global Logistics Powerhouse
Frasers Logistics & Commercial Trust, or FLCT, manages a vast network of 113 properties across five countries, focusing heavily on the lucrative logistics and industrial sectors.
In its recent 1QFY2026 business update, the REIT showed impressive operational progress.
Portfolio occupancy climbed to 96.2%, a notable jump from 95.1% in the previous quarter.
The heavy lifting was done by Alexandra Technopark in Singapore, where occupancy surged to 86.3% as at 31 December 2025, after the manager successfully leased out the majority of the space vacated by Google.
While the commercial side saw a slight negative rental reversion of 1.6% due to these renewals, the logistics and industrial segment remained a powerhouse with a staggering 36.4% positive rental reversion.
At a unit price of S$1.01, investors can look at a trailing distribution yield of approximately 5.9%.
Encouragingly, FLCT’s financial position looks healthy, with gearing improving to 34.8% and a comfortable debt headroom of S$592 million.
With borrowing costs holding steady at 3.1% and a healthy interest coverage ratio of 4.1x, the REIT is well-placed to navigate the current environment.
Investors will want to watch whether the newly secured leases at Alexandra Technopark commence on schedule by 3QFY2026, as this will be a critical driver for any future recovery in distributions and a sustained yield advantage over traditional savings.
Get Smart: Building a Resilient Income Stream
Investing in REITs is a marathon, and out-earning CPF rates requires picking managers who can adapt to changing tides.
Whether it is SGREIT’s clever refinancing, MPACT’s strategic shift back to the Singapore market, or FLCT’s success in filling large vacant spaces, these trusts demonstrate the active management necessary for long-term success.
While interest rate volatility remains a factor to watch, the combination of high occupancy and positive rental reversions across these three stocks provides a solid foundation.
By staying disciplined and focusing on high-quality assets, you can build a portfolio that delivers dependable, market-beating passive income for years to come.
The world’s gotten unpredictable, but some Singapore companies have quietly kept thriving. You’ve probably seen them in your daily life. And yes, they’ve kept paying dividends through it all. Meet 5 resilient stocks built to navigate global storms. Get the free report here and see how they’ve done it.
Follow us on Facebook, Instagram and Telegram for the latest investing news and analyses!
Disclosure: Calvina Lee does not own any of the stocks mentioned.