
November is shaping up to be a busy month for dividend investors in Singapore.
Three Straits Times Index (SGX: ^STI) blue chips will make payouts within 17 days of each other.
| Company | Ticker | Latest reporting period | Dividend payment date |
|---|---|---|---|
| Singapore Exchange Limited | SGX: S68 | FY2026 (ended 30 June 2026) | 10 November 2026 |
| Keppel DC REIT | SGX: AJBU | 9M2026 (ended 30 September 2026) | 23 November 2026 |
| Frasers Centrepoint Trust | SGX: J69U | FY2026 (ended 30 September 2026) | 27 November 2026 |
Here’s the thing: a payment date only tells you when the cash arrives.
It won’t tell you whether the next payment will be as large.
The business behind it will.
Can SGX keep raising its dividend?
Singapore Exchange Limited (SGX: S68), or SGX, runs the only stock market in Singapore.
When investors trade more, SGX earns more.
For the fiscal year ended 30 June 2026 (FY2026), net revenue rose 13.9% year on year (YoY) to S$1.5 billion.
Revenue from Equities – Cash segment climbed 28.1% to S$502.9 million as the securities daily average traded value (SDAV) rose 34.9% to S$1.8 billion.
Net profit grew at a slower 7.8% to S$698.4 million, impacted by a S$53.4 million goodwill impairment on Scientific Beta alongside softer investment gains.
Excluding the impairment and other one-off items, adjusted net profit rose 24.6% to S$759.5 million.
What about cash?
Free cash flow – the lifeblood of any dividend – remained robust at S$788.8 million, up 2.0% YoY, even as capital expenditure increased to S$94.2 million for core technology upgrades.
SGX also held S$1.8 billion in cash against S$628.2 million in borrowings.
In other words, it has net cash.
Shareholders will have received S$0.57 per share for FY2026 once the final dividends are paid, up from S$0.375 a year ago.
But that figure blends two different payouts:
- Ordinary dividends: S$0.445 per share
- One-off additional dividend: S$0.125 per share
The one-off portion may not return.
Management has guided for quarterly dividend increases of 0.25 cents through FY2028.
It also expects medium-term revenue growth of 6% to 8%, excluding treasury income.
On the flip side, busy trading years don’t always repeat.
Expenses are also set to climb 6% to 8% in FY2027.
Can FCT keep its record DPU?
Frasers Centrepoint Trust (SGX: J69U), or FCT, is Singapore’s largest suburban retail mall owner.
Think Northpoint City, Causeway Point and Waterway Point.
For the fiscal year ended 30 September 2026 (FY2026), gross revenue rose 14.2% YoY to S$444.9 million, while net property income (NPI) grew 15.7% to S$321.7 million.
Distribution per unit (DPU) expanded 2.0% to a record S$0.1235, with second-half DPU up 2.6% at S$0.06214.
Most of the growth came from Northpoint City South Wing, which FCT acquired in May 2025.
FY2026 was its first full year in the portfolio.
Retail committed occupancy stood at 99.7% excluding NEX.
Why did DPU lag NPI by so much?
FCT issued new units in April 2025 to help fund the acquisition, spreading income across more units.
Joint-venture distributions also fell 11.7% YoY, as a one-off special dividend did not recur.
Borrowing is getting cheaper.
FCT’s average cost of debt fell to 3.2% from 3.8% a year ago.
The trust also sold White Sands on 30 September 2026 and will use the proceeds to repay borrowings.
That will bring aggregate leverage down from 38.7% to 36.8% on a pro forma basis.
The number to watch is tenants’ sales.
They grew 1.3% YoY, well below the FY2026 rental reversion of 6.6%.
Rents can’t outrun sales forever.
NEX’s second-phase asset enhancement initiative (AEI) also begins in January 2027, and the works may weigh on income.
Is Keppel DC REIT’s DPU growth here to stay?
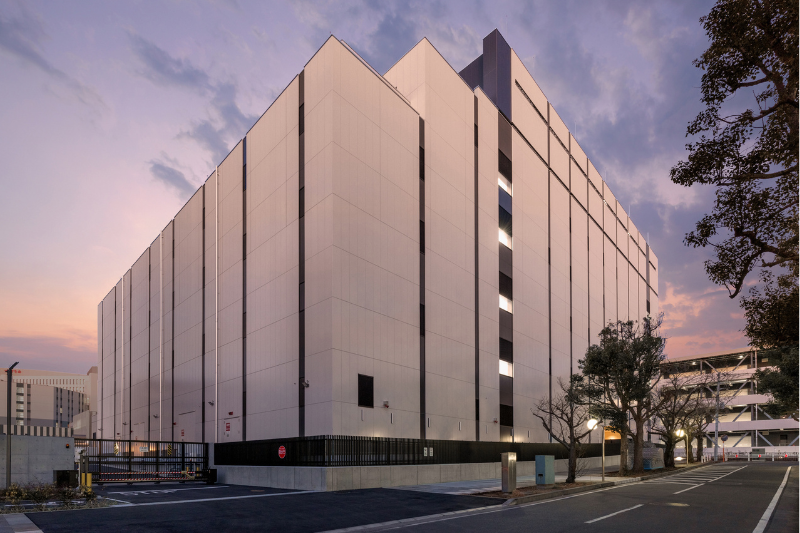
Keppel DC REIT (SGX: AJBU) owns 27 data centres across 10 countries, with Asia Pacific making up 87.4% of the portfolio.
For context, the REIT’s latest numbers cover the first nine months of 2026 (9M2026), not a full year.
Gross revenue rose 13.3% YoY to S$365.3 million and DPU climbed 11.7% to S$0.0857 cents.
Rents are doing much of the work.
Rental reversion averaged around 14% for 9M2026 and picked up to around 16% in the third quarter (3Q2026).
The acquisition of Tokyo Data Centre 3 helped too, and occupancy improved to 93.0%, up from 92.5% in 2Q2026.
Not everything went its way.
The REIT lost income from Cardiff Data Centre and divested Kelsterbach Data Centre.
Finance costs also rose.
There’s also a dilution effect.
A September 2026 private placement increased the number of units before the new Tokyo assets started earning income.
That’s a timing issue, not a sign of weaker properties.
On 1 October 2026, Keppel DC REIT completed its purchase of an 88.62% interest in Tokyo Data Centres 4 and 5 for around S$1.4 billion.
Both are fully occupied, and their in-place rents sit more than 30% below market.
Management expects the deal to lift DPU by 2.0%.
The catch? Pro forma aggregate leverage rises to 38.8% from 36.2%.
Power constraints continue to limit new data centre supply in Asia Pacific.
That scarcity supports rents.
The next few quarters will show whether the Tokyo assets deliver the expected uplift.
Get Smart: Separate what repeats from what doesn’t
Every dividend has a recurring core.
Some also carry a layer that may not come back.
SGX makes this easy by labelling its one-off dividend.
Other effects take more digging, like FCT’s missing joint-venture special or Keppel DC REIT’s placement dilution.
When the next results arrive, ask whether the recurring part of your payout grew.
If it did, your income is on firmer ground.
Don’t let market uncertainty hijack your financial dreams. While headlines scream gloom, 5 Singapore companies have been quietly building wealth and paying reliable dividends. You’re probably overlooking them. Discover these resilient giants and their secrets to sustained income, even through global storms. Click here to download your free report now and secure your financial future!
Follow us on Facebook, Instagram, Telegram and YouTube for the latest investing news and analyses!
Disclosure: The Smart Investor owns shares/units of SGX, FCT and Keppel DC REIT.