Singapore’s engineering stocks rarely make headlines in a bull market environment.
Unlike high-growth tech and banking stocks, Singapore’s blue-chip engineering firms quietly generate long-term visibility and recurring earnings from defence, energy infrastructure, marine engineering and utilities.
While investors chase the high-growth prospects of the tech sector or the high yields of banks, companies like ST Engineering (SGX: S63) or Seatrium (SGX: 5E2) work in the background.
As the market is seeing increasingly fewer instances of momentum trading for profit, these blue chip names are increasingly gaining traction.
These companies – though often labelled “boring” – may emerge as the hidden winners in the year ahead.
Why Engineering Stocks Were Overlooked
Engineering stocks have historically served as a test of patience for investors.
This has been largely because of their “lumpy” earnings, which have been a result of long business cycles.
The key issue here is that the distortion of short-cycle perceptions of performance comes from the nature of the longer-cycle industries.
Ultimately, accepting this short-term “boredom” is the necessary price of admission for achieving long-term compounding success.
Structural Tailwinds Supporting the Engineering Sector
The engineering sector is expected to see continued structural increases caused by several very distinct structural shifts in the industry over the course of the next five years.
For example, in response to the increasing geopolitical instability across the world, global defence spending has risen to an all-time high.
National Oil Companies (NOCs) in the Asia Pacific and Middle East are projected to invest $110 billion or more in infrastructure modernisation.
This capital expenditure represents a significant tailwind for engineering firms specializing in offshore energy.
Furthermore, the shift towards large-scale development in offshore wind, hydrogen and grid storage is creating a robust pipeline of opportunities, expected to drive consistent growth for several years.
Defence and Aerospace: Steady Growth Anchors
ST Engineering continues to lead the industry with a robust contract pipeline.
In the first nine months of 2025 (9M2025), it secured S$14 billion in new contracts, bringing its record order book to S$32.6 billion and providing strong revenue visibility well into 2026 .
This is underpinned by steady defence and public security projects, which provide a foundation of long-term stability.
With the closure of the loss-making satellite business in 2025, ST Engineering enters 2026 with a cleaner earnings profile and an improved outlook for profitability.
However, execution quality and book-to-bill ratio remain critical; ST Engineering must maintain operational discipline to successfully translate its massive backlog into significant earning growth.
Energy and Marine Engineering: Cyclical but Recovering
The cyclical patterns of energy and marine engineering industries are still continuing, but with the recovery of backlogs and positive signals from various segments, things are looking better.
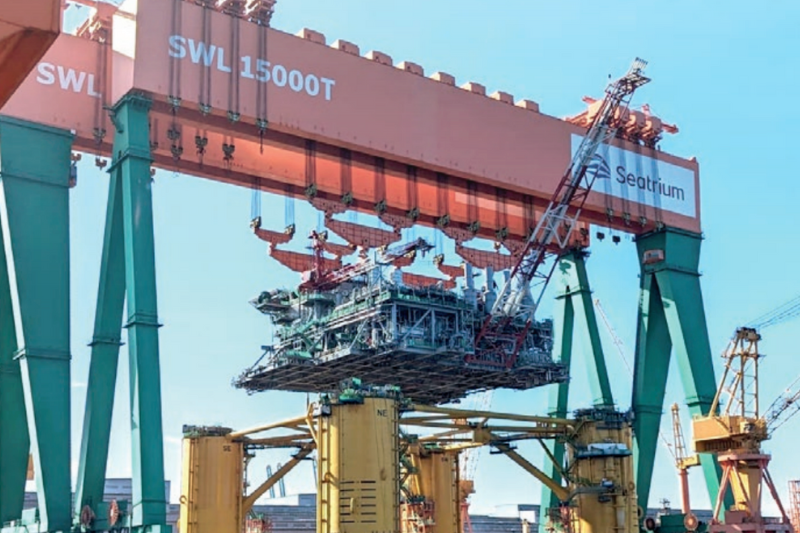
Seatrium (SGX: 5E2) serves as a prime example, boasting a net order book of S$16.6 billion with revenue visibility extending through 2031.
A key catalyst for the company is the anticipated conclusion of low-margin legacy contracts by the end of FY2026.
This transition is expected to pave the way for a pivot toward higher-margin offshore renewable and energy projects, significantly improving the company’s profitability profile.
Yangzijiang Shipbuilding (SGX: BS6) also sustained strong commercial momentum through 9M2025, securing US$2.17 billion in new contract wins.
This brings its total order book to a staggering US$22.8 billion, with a significant portion now concentrated in high-value “green” dual-fuel and LNG (liquefied natural gas) vessels.
Both companies look well-positioned to respond to future trends over the 2028 through 2030 time frame.
Infrastructure and Utilities Engineering: Stability Through Integration
Sembcorp Industries (SGX: U96) integrates engineering expertise with utilities and renewable energy operations, offering a hybrid model that balances growth with defensive cash flow.
In the first half of 2025 (1H2025), the group reported a net profit of S$536 million, underpinned by stable utilities earnings and a 27% year-on-year (YoY) growth in its renewables segment from higher capacity and wind resources.
The ability of utility providers to establish long-term contracts for offtake supply has allowed the company to create integrated energy solutions, thereby generating significant and consistent revenue, allowing for stability in the cyclical performance of the business.
The hybrid business model of energies, engineering project execution and renewable expansion is designed to uniquely position Sembcorp to experience both long-term growth and positive returns while presenting opportunities to play in the infrastructure and energy transition space in 2026.
What Investors Should Watch
The performance of engineering companies will hinge less on quarterly revenue swings and more on the quality and replenishment of their order books, which signal future earnings visibility and growth potential.
Investors should monitor order book growth, project margins and cost-control discipline, as these factors determine how efficiently companies convert signed contracts into profitable deliveries.
Cash flow conversion and balance sheet strength are equally important, as they provide the resilience to weather cyclical downturns or delayed project payments.
A customer base that consists of government, or sustainable institutional clients will provide a predictable revenue stream.
Get Smart: Visibility Matters More Than Excitement
Singapore-based engineering companies are leading globally in meeting critical security, energy and infrastructure demands.
While they may lack the volatile growth profiles of technology IPOs, they offer investors what is increasingly rare in today’s market: stable long-term earning power, consistent cash flow, and high predictability.
Strategic exposure to industry leaders – such as ST Engineering (defense), Seatrium and Yangzijiang (marine and energy backlogs), and Sembcorp (hybrid utilities) – provides a blend of high-quality execution and structural growth.
For the disciplined investor, these firms represent a compelling opportunity for resilient returns.
The world’s gotten unpredictable, but some Singapore companies have quietly kept thriving. You’ve probably seen them in your daily life. And yes, they’ve kept paying dividends through it all. Meet 5 resilient stocks built to navigate global storms. Get the free report here and see how they’ve done it.
Follow us on Facebook, Instagram and Telegram for the latest investing news and analyses!
Disclosure: Darien does not hold any of the above-mentioned stocks.