
Real Estate Investment Trusts (REITS) are favoured by income investors due to their steady distribution payout.
Recently, CapitaLand Integrated Commercial Trust (SGX: C38U), or CICT, raised its distribution, pushing its trailing annualised yield close to 5%.
The question that may weigh on investors’ minds is: With CICT raising its distributions, is it a buy now?
Background
CICT is Singapore’s largest REIT. The trust has a diverse portfolio of 26 properties valued at S$27 billion as of 31 December 2024. 21 of the trust’s properties are in Singapore with the remaining in Germany (two) and Australia (three).
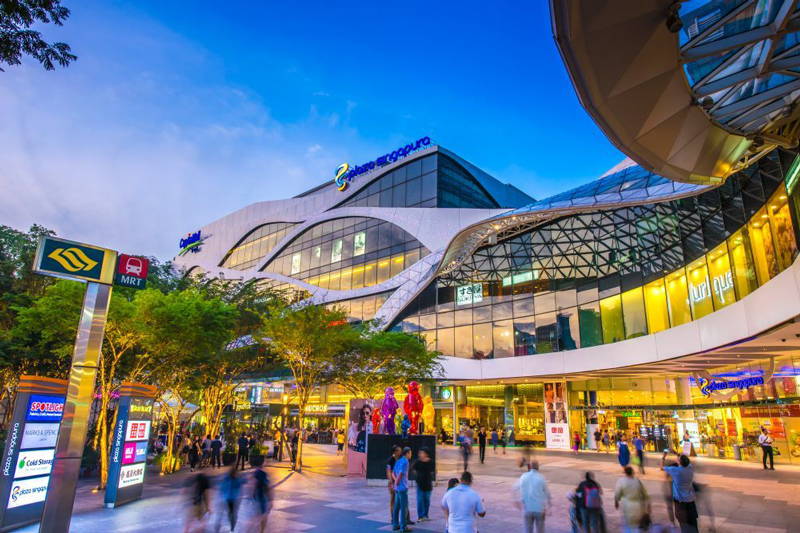
The portfolio is focused on offices (mainly in Singapore’s central business district), retail malls, and integrated developments. You might have visited some of their local properties before, for example, Plaza Singapura, CapitaSpring, and Raffles City.
Recent Performance
CICT’s share price has rallied 21% year-to-date, excluding distributions, to S$2.34.
In the first half of 2025 (1H 2025), the trust’s revenue was down slightly by 0.5% year-on-year (YoY) to S$787.6 million. Net property income (NPI) similarly slipped 0.4% to S$579.9 million.
But CICT’s distributable income rose 12.4% YoY because of improved performance from existing properties and contributions from ION Orchard; CICT had acquired a 50% stake in ION Orchard in October 2024.
Lower interest expenses, because of the interest rate easing cycle and lower gearing, also led to higher distributable income.
Ultimately, CICT’s distribution per unit rose 3.5% YoY to S$0.0562 per share, continuing the steady growth post-COVID.
At its share price of S$2.34, the REIT has a trailing annualised dividend yield of 4.7%. This is slightly lower than the average yield of around 5% of other Singapore blue-chip REITs1.
1 Mapletree Logistics REIT (SGX: M44U), Frasers Centrepoint Trust (SGX: J69U), Keppel REIT (SGX: K71U), Suntec REIT (SGX: T82U)
What Sets CICT Apart
CICT’s portfolio includes first-rate retail malls, such as Ion Orchard, Bugis+, and Plaza Singapore.
The core of its office buildings sits in the heart of Singapore’s central business district and these offices include Capital Tower, Six Battery Road, and CapitaSky.
In August this year, the trust acquired the remaining 55% stake in CapitaSpring which it did not own.
CICT has seen strong rental recovery recently.
The overall occupancy rate across its portfolio is 96.3% as of 30 June 2025, with healthy tenant renewal rates of 81.8% for its retail properties and 76.8% for its office properties.
CICT also saw positive rental reversions of 7.7% and 4.8% YoY for its retail properties and office properties, respectively, showcasing its ability to raise rents.
The trust is well-diversified.
For 1H 2025, its retail portfolio contributed S$218.8 million in NPI, or 37.7% of total NPI, up 3.5% YoY.
Its office portfolio raked in S$183.6 million in NPI (31.7%), down 6.8% YoY.
The integrated developments make up 30.6% of total NPI with an NPI of S$177.5 million, growing 2% from the prior year.
CICT’s low leverage is also a strength. As of 30 June 2025, it has an aggregate leverage ratio of just 37.9%.
Risks / Considerations
A risk for CICT is the possibility of higher interest rates, which could lead to lower distributable income and thus DPU.
Shifts in consumer behaviour, such as the increase in online shopping compared to physical shopping, is another risk.
It could reduce footfall in CICT’s retail properties, leading to a decrease in CICT’s NPI.
Another risk is societal desire for flexible working arrangements, including work-from-home, which would reduce utilisation of office space.
This could decrease demand for CICT’s offices.
The risk is partially mitigated given the prime nature of the trust’s office portfolio.
Lastly, after the strong year-to-date rally in CICT’s share price, the market could have fully priced in its growth and strong fundamentals.
Putting it altogether
CICT remains one of the safest, most liquid REITs in Singapore.
Its recent increase in distribution underscores management’s confidence in recovery and growth.
Given its decent yield of 4.7%, CICT should be considered by investors seeking long-term stable income.
But investors should be mindful of the risks, such as higher interest rates, which could hurt the trust’s DPU, and the possible shift in consumer and work-from-home trends, which might hamper demand for the trust’s properties and higher interest rates.
Get Smart: CICT – A Solid Bedrock for Any Dividend Portfolio
CICT’s stable yield of nearly 5%, coupled with its well-diversified portfolio of assets, makes it a compelling dividend stock.
The REIT offers scale, safety, and dependable distributions for investors seeking consistent income from Singapore’s office and retail real estate.
Although the trust still faces risks, just like any other business, it could do well as a vanguard of a dividend investor’s portfolio.
Some companies cut dividends in a downturn. These 5 didn’t.
Find out which Singapore blue chips have weathered past chaos…and why they could be your portfolio’s anchors in the next wave of downturn. Download the report free.
Follow us on Facebook, Instagram and Telegram for the latest investing news and analyses!
Disclosure: Wesley does not own shares in any of the companies mentioned.