CapitaLand Integrated Commercial Trust (SGX: C38U), or CICT, is reshaping its portfolio.
Paragon, a freehold retail and medical asset on Orchard Road, joined the REIT on 1 July 2026.
Asia Square Tower 2 has left the REIT’s portfolio.
Further down the line, CICT’s S$1.1 billion commercial development at Hougang Central could add another major source of income.
How did CICT fare in the first half of 2026?
Two engines drove CICT’s distribution growth in the first half of 2026 (1H 2026): full ownership of CapitaSpring and Gallileo’s handover to the European Central Bank.
Gross revenue rose 7.5% year on year to S$846.8 million.
Net property income (NPI) grew 8.7% to S$630.5 million.
Distributable income climbed 13.3% to S$466.7 million.
Distribution per unit (DPU) increased 7.1% to S$0.0602 for 1H 2026.
Retail was the softer side.
Retail gross revenue fell 3.9% and retail NPI slipped 3.7%, largely because CICT divested Bukit Panjang Plaza in February 2026.
Tenant sales per square foot grew 1.6% and shopper traffic rose 2.4%.
Meanwhile, office rental reversion reached 6.5% in 1H 2026, up from 4.8% a year earlier.
Retail reversion eased to 4% from 7.7%.
How does the Paragon and Asia Square Tower 2 swap work?
CICT completed its Paragon acquisition on 1 July 2026.
The deal carries an agreed property value of S$3.9 billion and an overall net yield of 3.9%.
Paragon starts contributing to CICT’s income from the third quarter of 2026 (3Q 2026).
Asia Square Tower 2 headed the other way.
The divestment was completed on 17 September 2026 at an exit yield of 3%.
The sale is expected to bring in about S$2.45 billion of net proceeds.
What about debt?
CICT’s aggregate leverage stood at 37.4% on 30 June 2026.
The cost of debt fell to 2.9% from 3.4% a year ago.
Interest cover rose to 3.9 times from 3.3 times.
Fixed-rate borrowings made up 78% of total debt, down from 81%.
Which asset enhancement projects come next?
CICT has five asset enhancement initiatives (AEIs) lined up through to 2028.
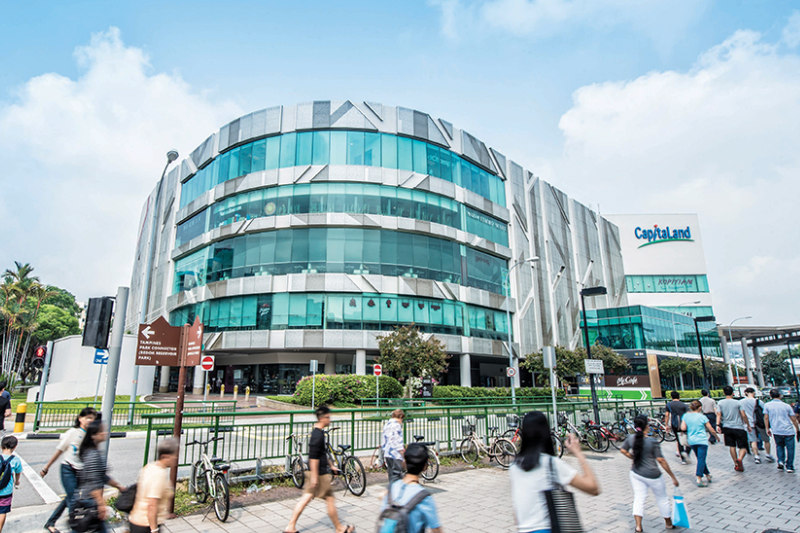
Tampines Mall comes first.
The mall’s AEI completes in 3Q 2026 at a cost of about S$24 million, with a targeted return on investment (ROI) of about 7%.
Next, CICT expects its Raffles City Tower upgrading to finish in 4Q 2026.
Lot One Shoppers’ Mall follows in 1Q 2027, with about S$37 million of capital expenditure and a targeted ROI above 7%.
Two projects are due to start in 3Q 2026.
Capital Tower’s AEI costs about S$25 million and should be completed in 4Q 2027.
The second is also the biggest AEI.
It covers Plaza Singapura and The Atrium@Orchard.
CICT plans to spend about S$160 million there for a targeted ROI of 6% to 7%, with completion in 4Q 2028.
What could Hougang Central add?
Hougang Central’s commercial component will offer about 300,000 square feet of net lettable area.
CICT puts the development cost at about S$1.1 billion.
Based on the valuer’s estimated net income, the yield on cost should exceed 5%.
The project sits in the design and planning stage.
Construction should begin in 2027, subject to planning approvals, with completion in 2030 or 2031.
Management expects no DPU impact during the development period.
Once complete, Hougang Central could give CICT’s DPU another major boost.
What risks should unitholders watch?
Paragon’s lease expiries stand out.
Retail leases making up 30.6% of Paragon’s gross rental income expire in 2027.
That is a large slug of space to re-let in a single year.
Those renewals will largely decide whether Paragon grows income beyond the 1.7% accretion that management has modelled.
The Johor Bahru-Singapore Rapid Transit System (RTS) Link poses a second risk for retail.
Its impact is anyone’s guess, but investors cannot assume there will be none, especially for malls in the west of Singapore.
Get Smart: Follow the DPU, not the deals
Asset swaps and AEIs make big headlines.
For unitholders, the real test is whether the REIT can lift its DPU over time.
With CICT, watch where aggregate leverage settles now that the Asia Square Tower 2 sale is complete.
Then track the rents Paragon secures as its 2027 leases come up for renewal.
If both head in the right direction, the AEI pipeline and Hougang Central give CICT a path to growing DPU into the next decade.
Imagine receiving steady rent increases for more than two decades. It sounds unusual, but one healthcare REIT already has rental escalations locked in until around 2042. Income visibility like this is hard to find today. We break down how this REIT built such dependable cash flow in our FREE dividend report and how it could strengthen a retirement portfolio. Get the free report here.
Follow us on Facebook, Instagram, Telegram and YouTube for the latest investing news and analyses!
Disclosure: Chin Hui Leong owns units in CICT.