September 2026 brings a cluster of interim dividend payments from three members of the iEdge Singapore Next 50 Index.
Pan-United Corporation (SGX: P52) pays on 4 September, followed by Hong Leong Asia (SGX: H22) on 9 September, with First Resources (SGX: EB5) rounding out the trio on 10 September.
Each of these companies has bumped up its interim payout by 50% or more year on year (YoY).
A substantial dividend hike naturally catches the eye, but for long-term income investors, the percentage increase is only part of the story.
What matters far more is how those higher payouts were funded – and whether that capital source is repeatable.
Can Singapore’s construction boom sustain a 50% dividend increase?
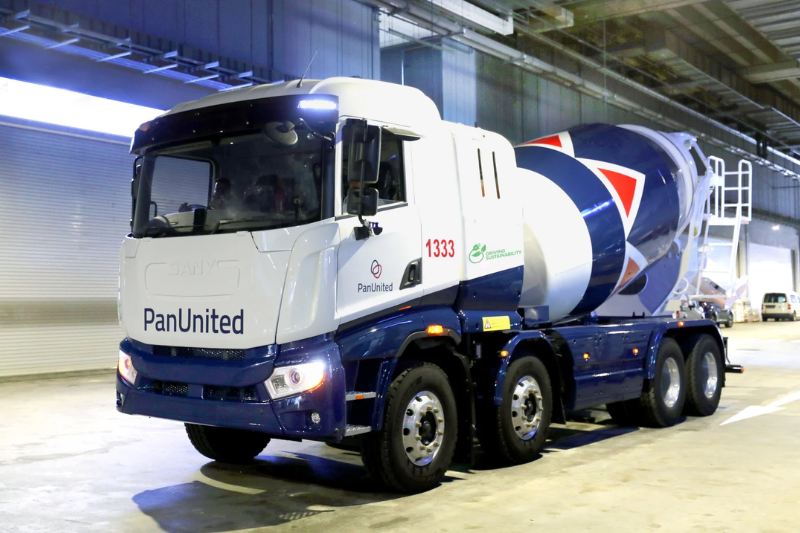
Pan-United declared an interim dividend of S$0.015 per share, up 50% from S$0.010 a year ago.
Singapore’s largest ready-mix concrete supplier generated revenue of S$549.6 million for the first half of 2026 (1H2026), a 37% YoY increase.
Net profit attributable to shareholders rose 49% to S$30.6 million, while EBITDA expanded 48% to S$60.8 million, bolstered by operating leverage and efficiency gains through its AiR Digital platform.
Free cash flow improved to S$7.4 million, up from S$1 million a year prior, while capital expenditure moderated to S$19.5 million.
A S$26 million working capital build in trade receivables – in step with higher revenue – kept a lid on broader cash generation.
That said, the balance sheet remains conservative: as of 30 June 2026, Pan-United held S$86.2 million in cash against S$21 million in total borrowings, excluding lease liabilities.
Looking ahead, the demand backdrop remains supportive.
The Building and Construction Authority (BCA) projects total construction demand to reach S$47 billion to S$53 billion for 2026, anchored by megaprojects like Changi Airport Terminal 5, the Marina Bay Sands expansion, new healthcare infrastructure, and ongoing MRT line extensions.
Contractors had secured S$31 billion of that overall pie as of June 2026, though persistent energy price volatility and input cost pressures remain operational watchpoints.
What’s behind the 50% payout increase at Hong Leong Asia?
Hong Leong Asia raised its interim payout 50% to S$0.03 per share, up from S$0.02 last year, with no special dividend declared.
Group revenue rose 17.6% YoY to S$3.1 billion for 1H2026, while profit attributable to owners surged 64.1% to S$91.9 million.
Top-line expansion was led by its powertrain division, Yuchai, which logged a 16.8% revenue increase on the back of 277,684 engine units sold – up 10.9% YoY.
Heavy-duty (HD) truck engine sales jumped 47.3%, significantly outpacing the 13.1% growth in HD truck sales reported by the China Association of Automobile Manufacturers (CAAM).
Meanwhile, the building materials division posted a 24.1% revenue gain on higher ready-mix and precast concrete volumes, partially offset by lower cement sales.
Overall gross margin widened to 19.1% from 16.1%, helped by a richer product mix and reduced warranty claims.
Cash flows were tighter than last year, however.
Free cash flow declined 35.7% to S$217.1 million as working capital absorbed funds, reversing the previous period’s inflows.
Even so, the balance sheet provides a substantial cushion.
The group held S$1.8 billion in cash and short-term deposits against S$757.2 million in loans and borrowings at the end of June, leaving a net cash buffer of approximately S$1.1 billion.
Management expects a satisfactory full-year performance, supported by steady demand for data centre backup power and regional construction momentum.
How did First Resources fund a 77.8% dividend increase?
First Resources led the trio on payout growth, declaring an interim dividend of S$0.08 per share – a 77.8% increase over the S$0.045 distributed last year.
The integrated palm oil producer generated US$973.6 million in revenue for 1H2026, up 44.5% YoY, while net profit attributable to owners climbed 57.4% to US$234.9 million. Underlying net profit, which strips out biological asset fair value adjustments, rose 42.2% to US$216.2 million.
Note that these figures reflect a structural shift in operations.
First Resources completed its acquisition of PT Austindo Nusantara Jaya in May 2025, meaning the prior-year period included only two months of consolidated operations versus a full six months in 1H2026.
Higher sales volumes, firmer processing margins, and the extended integration of the acquired assets drove the performance.
Cash flow generation saw a noticeable turnaround, with free cash flow moving from a negative US$84.7 million to a positive US$100.6 million, supported by an operating cash flow surge to US$210.7 million.
Net gearing stood at a manageable 0.40x against gross borrowings of US$887.4 million.
Total cash reserves ended the period at US$229.2 million, though US$115.4 million of that balance remains restricted under Indonesia’s mandatory export proceeds retention framework.
Near-term variables to monitor include Middle East geopolitics affecting crude oil and biodiesel pricing, potential demand support from Indonesia’s proposed B50 mandate, and possible El Niño weather impacts on palm yields later in the crop cycle.
Get Smart: What Separates a Dividend Increase That Lasts From One That Doesn’t?
A 50% dividend hike is an effective headline, but a single half-year report tells you where a company has been, not where its payout is going.
Having net cash on the balance sheet offers a helpful safety net during quiet periods, but net cash isn’t an organic income stream.
To determine whether a higher payout can be sustained, investors need to see free cash flow cover those dividends reliably across different market cycles – not just during a single strong half-year.
The next time any company raises its dividend, ask what funded the increase.
The answer will tell you more than the size of the payout ever could.
Imagine owning businesses that continued paying shareholders even when markets were falling. That’s the appeal of dividend investing done well. Our FREE report reveals 6 SGX companies that paid dividends every single year for two decades, through the Global Financial Crisis, COVID-19, and 2022’s rate shock. Start building the kind of income stream that could fund a more comfortable retirement. Get your free report here.
Follow us on Facebook, Instagram, Telegram and YouTube for the latest investing news and analyses!
Disclosure: The Smart Investor does not own any of the stocks mentioned.