AEM Holdings (SGX: AWX) delivered a total return of over 443% year to date as of last Friday (18 September 2026), according to Fiscal.ai.
AEM makes test handlers and systems for the semiconductor industry.
A return of 443% in under nine months is eye-catching.
The company’s first-half results provide reasons why the stock is gaining.
What drove AEM’s first-half performance?
Revenue rose 29.9% year on year to S$247.2 million for the first half of 2026 (1H 2026).
Net profit hit S$31 million, a 10-fold increase from S$3.1 million a year ago.
The margin expansion is worth highlighting.
Gross margin rose from 25.4% to 33.1% on a better segment mix, leading to net margin reaching 12.5%, up from 1.6% in 1H 2025.
Test Cell Solutions drove the results.
Revenue from this segment grew 52.5% year on year to S$180.9 million, around 73% of group revenue.
A single fabless AI and high-performance computing (HPC) customer became AEM’s top revenue contributor for the half.
This is a meaningful shift.
The message?
AEM’s revenue base is broadening beyond its traditional PC/Foundry customer.
This is an important development, as the business is becoming less concentrated and more diversified.
The dividend reward
AEM last declared an interim dividend in 1H 2022.
Four years on, it paid S$0.024 per share for 1H 2026.
Management could have stuck with a once-a-year final dividend.
It chose to bring back the interim.
That tells you it expects to keep paying.
Management raised full-year 2026 revenue guidance to S$630 million to S$680 million, up from S$550 million to S$600 million.
AEM attributed the increase to its fabless AI/HPC ramp and its PC/Foundry customer’s adoption of the Asynchronous Modular Parallel Smart (AMPS) platform.
For the first time, AEM also guided towards earnings per share of between S$0.245 and S$0.275.
Where does AEM’s growth go from here?
AEM has built its strategy around five business pillars.
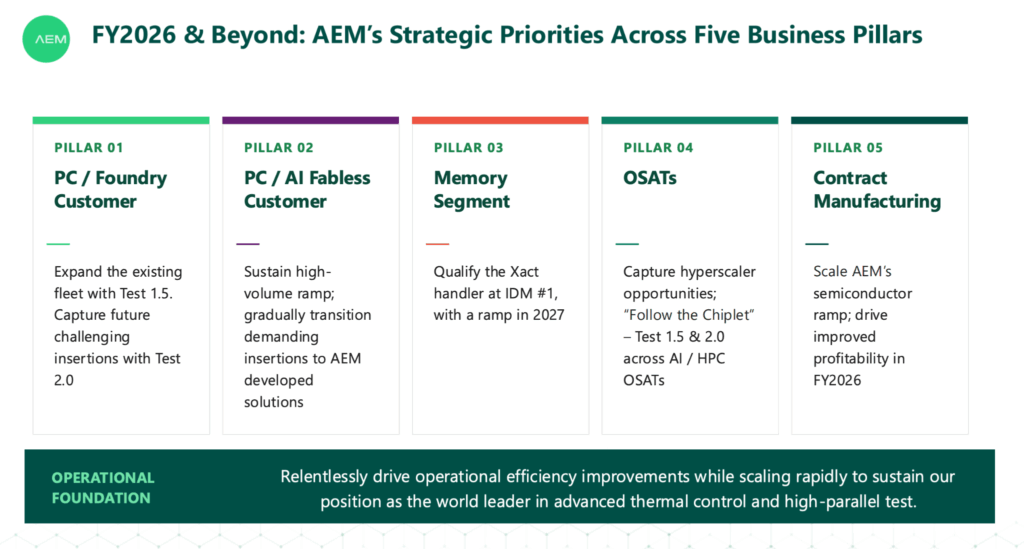
Two are already contributing to revenue and margins.
Three are still in development.
Pillar 01 centres on its PC/Foundry customer.
AEM does not name this customer, but it is widely presumed to be Intel (NASDAQ: INTC).
The semiconductor equipment maker plans to expand the installed fleet through Test 1.5 upgrades.
The harder future insertions would go to Test 2.0.
It’s worth decoding these labels.
Think of the configurables and collaterals under Test 1.5 as the razor blades.
The full systems and handlers under Test 2.0 are the razors.
AEM is building a razor-and-razor blade business.
Pillar 02 targets its PC/AI fabless customer.
Most analysts point to Advanced Micro Devices (NASDAQ: AMD) as the likely name.
AEM aims to sustain the high-volume ramp and gradually shift more demanding insertions onto its own solutions.
The semiconductor firm credits these two pillars for its raised 2026 guidance.
The company’s order backlog for the AMPS platform now exceeds S$400 million, and both the AI/HPC fabless and PC/Foundry customers continue to add orders.
The remaining three pillars still need to prove themselves.
Pillar 03 (Memory) requires AEM to qualify its Xact handler at its first memory integrated device manufacturer (IDM).
The ramp is pencilled in for 2027.
This would mark AEM’s entry into the memory testing market.
Pillar 04 taps on outsourced semiconductor assembly and test companies (OSATs) and runs through ASE Technology (NYSE: ASX).
AEM’s approach is to track the chiplet as it moves through AI/HPC OSATs.
The channel gives AEM a path to hyperscalers it could not have reached alone.
Pillar 05 (Contract Manufacturing) aims to support AEM’s semiconductor ramp and lift its own profitability.
What about the cash flow?
Income investors, though, have their eyes on AEM’s free cash flow.
And for good reason.
AEM’s free cash flow fell to just S$2 million in 1H 2026, down from S$37.4 million a year ago.
Operating cash flow dropped to S$12.5 million from S$46.4 million a year ago.
Where did the cash go?
Inventories consumed S$37.6 million and receivables another S$31.5 million.
Management says the inventory build supports second-half growth.
AEM has S$80 million in net cash to cover its dividend obligations.
Get Smart: Priced for the future, not the past
AEM grew net profit 10-fold in 1H 2026.
But its free cash flow fell to S$2 million.
Profit without cash flow is a promise, not proof.
To be fair, the future looks promising.
Two of AEM’s five pillars are delivering, and the AMPS backlog tops S$400 million.
For investors looking for dividends, the milestone to watch is whether AEM can convert profits into cash.
With more cash, the chances of higher dividends rise.
The world’s gotten unpredictable, but some Singapore companies have quietly kept thriving. You’ve probably seen them in your daily life. And yes, they’ve kept paying dividends through it all. Meet 5 resilient stocks built to navigate global storms. Get the free report here and see how they’ve done it.
Follow us on Facebook, Instagram, Telegram and YouTube for the latest investing news and analyses!
Disclosure: Chin Hui Leong owns shares of AEM.