In recent years, interest rates have weighed on Singapore REITs (S-REITs), putting a squeeze on distributions while financing costs climbed.
As a result, many companies responded by strengthening their balance sheets instead of chasing growth.
But with rates stabilising and refinancing risks easing, conditions are starting to look up.
With a possible REIT revival on the horizon, we look at which ones are positioned for higher DPUs (distributions per unit).
A Turning Point for REITs?
Lower or slowing interest rates can play a critical role in shaping REIT performance.
By reducing borrowing costs, rate cuts can enhance property values, lower financing expenses, and strengthen dividend-paying business models.
Occupancy rates have remained high across most property segments, with rental reversions staying generally positive.
Meanwhile, valuations remain well below historical peaks, despite signs that fundamentals are steadying.
The headwinds that held REITs back in recent years may now be losing strength.
What Drives DPU Growth in a Recovering REIT Cycle
DPU represents the cash an investor receives for each unit owned.
For example, if a REIT distributes S$1 million and has 10 million units, the DPU translates to S$0.10 per unit.
In a recovering REIT cycle, DPU growth is fueled by lower interest expenses from refinancing at better rates, which reduce finance costs.
Higher occupancy and positive rental revisions help lift rental income.
Asset enhancement initiatives also begin to lift rents and attract stronger tenant demand.
In summary, sustainable DPU growth is driven by rising cash flow, not optimism about the cycle.
Mapletree Pan Asia Commercial Trust (SGX: N2IU), or MPACT — Strong Balance Sheet Advantage
MPACT is backed by Mapletree Investments, a real estate group managing S$80.3 billion in assets as of 31 March 2025.
In the third quarter of FY2025/2026 (3QFY2025/2026), the trust announced a DPU of S$0.0205 – up 2.5% from last year’s S$0.02.
The amount available for distribution to unitholders climbed to S$108.2 million, a 3.3% increase compared to the same period last year.
The steady uptick suggests operating income becoming stabler even though rates remain moderately elevated.
By 31 December 2025, aggregate leverage hit 37.3%, and about 71.8% of borrowings stayed on fixed rates.
The interest coverage ratio sits at 3.1 times, and their debt maturity is well staggered, which adds a layer of financial stability.
With moderate gearing, most debt locked in at fixed rates, and refinancing risks under control, tMPACT is keeping interest expenses in check.
A strong balance sheet may not drive immediate growth, but it provides the foundation for DPU recovery.
Frasers Centrepoint Trust (SGX: FCT) — Rental Growth Engine
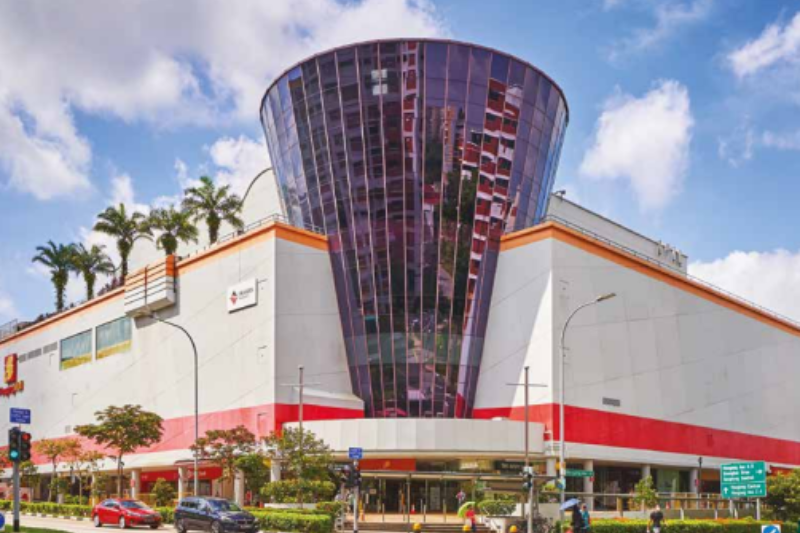
FCT’s main focus revolves around suburban retail malls that serve daily consumer essentials, such as Hougang Mall, Causeway Point, and Tiong Bahru Plaza.
As at 30 September 2025, retail assets made up 97.3% of its portfolio by valuation, with pure Singapore exposure and assets valued at around S$6.4 billion.
The trust’s committed occupancy was 98.1% in the first quarter of fiscal year 2026 (1QFY2026) and rose to 99.9% after former cinema spaces at Causeway Point and Century Square were successfully backfilled.
Shopper traffic grew 1.3% year on year (YoY), while tenant sales rose 2.7%, a tell-tale sign that tenant demand stays strong despite a cautious consumer backdrop.
With around 54% of its tenants providing essential services (as of 31 December 2025), FCT’s suburban malls tend to deliver steady, defensive cash flows.
The trust has paid a constant annual distribution since 2006.
For FY2025, FCT declared a full year DPU of S$0.12113, remaining fairly consistent over the past five years.
FCT is appropriate for those seeking more defensive and predictable income from essential services, with its organic rental growth compounding over time.
AIMS APAC REIT (SGX: O5RU), or AAREIT — Asset Quality and Occupancy Resilience
AAREIT is an industrial REIT with 28 properties across Singapore and Australia, with the bulk of its income in Singapore’s industrial sector.
Its portfolio spans logistics, business parks, high tech and manufacturing facilities, providing exposure to defensive and growth industries.
As at 31 December 2025, its portfolio occupancy stood at 95.4%, or 96.6% including committed leases, with positive rental reversions of 8.0% for 9MFY2026 – an indication that leasing momentum remains healthy despite a cautious macro environment.
AAREIT’s gross revenue increased by 1.4% YoY to S$141.1 million, while net property income rose 4.1% YoY to S$103.7 million.
Latest DPU saw a 2.5% YoY increase to S$0.07250.
Over the past five years, AAREIT’s annual DPU has recovered from pandemic lows and has remained between S$0.094 to S$0.099.
With aggregate leverage at 36.6% and no refinancing due until FY2027, AAREIT has the balance sheet stability to focus on growth and lift its DPU.
The REIT is an example of how high-quality industrial assets and disciplined capital management can position a REIT to benefit when demand strengthens.
Get Smart: The Best REITs Recover Before the Headlines
In 2026, investors should watch interest coverage, refinancing timelines, and free cash flow after interest.
Management discipline on leverage and acquisitions matters just as much.
Common mistakes to avoid in a REIT recovery: chasing the highest yield without checking sustainability, and ignoring balance-sheet risks.
A REIT revival does not lift all trusts equally.
Selectivity matters in a revival.
Those with strong balance sheets, resilient assets, and disciplined managers stand out.
Smart investors focus on DPU sustainability — and let the recovery unfold over time.
It almost feels like the government is paying companies to make you wealthier. Singapore’s new S$5 billion market boost could send fresh money into local stocks. We identified 5 companies positioned to benefit, including familiar names with surprising wealth potential. Our free report reveals these hidden opportunities before the money flows in. Download it now before it’s too late.
Follow us on Facebook, Instagram and Telegram for the latest investing news and analyses!
Disclosure: Joseph G. does not own shares in any of the companies mentioned.