Singapore REITs faced headwinds for most of the first half of 2025, with pressure from elevated high interest rates, which raised financing costs and weighed on valuations.
Yet, five REITs managed to deliver higher distributions per unit (DPUs), demonstrating resilient portfolio management and strong operational fundamentals.
Here’s how these five REITs rewarded investors even in a challenging macroeconomic environment.
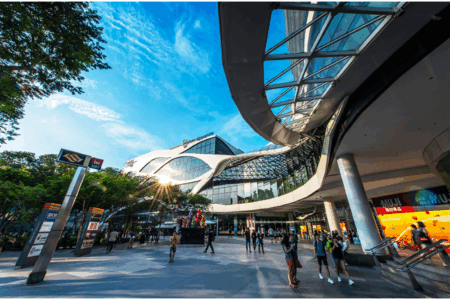
CapitaLand Integrated Commercial Trust (CICT, SGX: C38U)
CapitaLand Integrated Commercial Trust, or CICT, delivered a 3.5% year-on-year (YoY) increase in distribution per unit (DPU) to S$0.0562 for the first half of 2025 (1H2025), despite a marginal decline in revenue (down 0.5% to S$787.6 million).
Net Property Income (NPI) fell on the year by 0.4% to S$579.9 million, but distributable income surged 12.4% YoY to S$411.9 million, boosted by income contributions from the ION Orchard acquisition and lower interest expenses.
Committed occupancy remained high at 96.3% as of 30 June 2025, with the retail portfolio achieving a 7.7% rental reversion in 1H2025, while office portfolio saw a 4.8% rental reversion over the same period.
CICT remains positive on the planned asset management enhancement initiatives (AEIs) for Lot One and Tampines Mall, with a combined estimated cost of S$61 million, and management targeting a 7% return on investment for both projects.
On the acquisitions front, the purchase of the remaining 55% stake in CapitaSpring’s office tower looks to strengthen CICT’s presence in Singapore’s tight-supply office market.
CICT is benefiting from recovering retail traffic and steady office demand.
The trust has successfully combined leasing, AEIs, and portfolio reconstitution to grow assets and DPU, with notable initiatives including IMM Building’s S$48 million AEI and selective high-payoff projects such as CapitaSpring.
Through strategic divestments and reinvestments, CICT continues to enhance portfolio quality and deliver long-term value.
Keppel DC REIT (SGX: AJBU)
Keppel DC REIT is a data centre REIT with a portfolio of 24 data centres spread across 10 countries.
The total assets under management (AUM) of the REIT stood at around S$5 billion as of 30 June 2025.
For 1H2025, revenue climbed 34.4% YoY to S$211.3 million, with NPI rising 37.8% YoY to S$182.8 million.
DPU for 1H2025 increased by 12.8% YoY to S$0.05133, on the back of strong portfolio performance and contributions from recent acquisitions.
The trust also achieved 51% positive rental reversion, as demand for data centres is robust amid tight supply in Singapore.
The management anticipates that the positive trend will continue over the next 24 months.
Portfolio occupancy remains strong for the first half of the year, standing at 95.8% as of 30 June 2025, with a weighted average lease expiry (WALE) of 6.9 years.
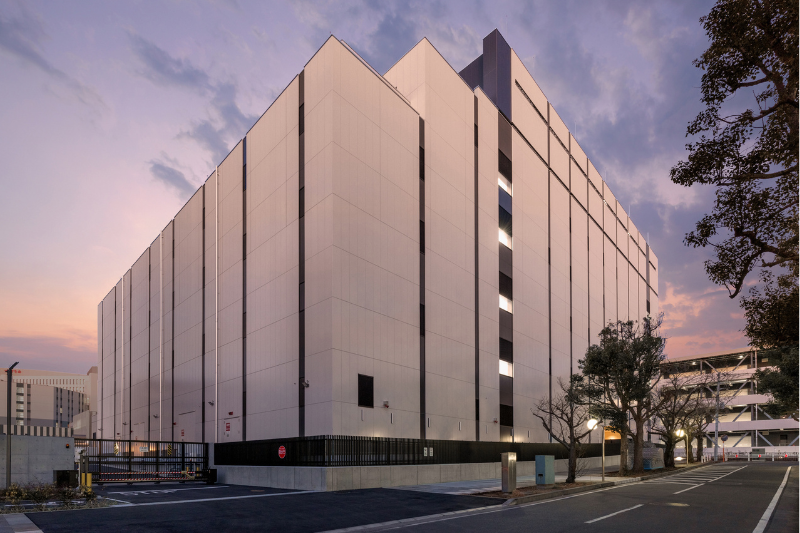
In September 2025, Keppel DC REIT announced the acquisition of Tokyo Data Centre 3 for JPY82.1 billion (approximately S$707 million).
The facility is fully leased to a leading global hyperscaler, and includes annual rent escalations over its 15-year term.
Keppel DC REIT continues to benefit from digitalisation tailwinds and resilient demand for data hosting, underpinning stable growth and long-term value creation.
Elite Commercial REIT (Elite UK REIT, SGX: MXNU)
Elite UK REIT is a Singapore-listed real estate investment trust (REIT) focused on investing in commercial properties across the United Kingdom.
The REIT recently declared a 10% YoY increase in (DPU to GBP 0.0154 (S$0.027).
As of 30 June 2025, Elite UK REIT’s portfolio occupancy was solid at 95.0%, benefitting from stable, long-term leases with government tenants.
The trust’s WALE stands at 2.9 years, with its niche focus on long leases and stable, mission-critical tenants, providing a reliable income stream and flexibility for future leasing opportunities.
However, currency movements between GBP and SGD can impact distributions for Singapore dollar unitholders.
Nonetheless, Elite UK REIT continues to maintain a resilient portfolio, combining stable occupancy, solid lease structures, and careful currency management to deliver consistent returns to unitholders.
AIMS APAC REIT (SGX: O5RU)
AIMS APAC REIT (AA REIT) is a Singapore-listed trust that invests in industrial, logistics, and business park properties across the Asia-Pacific region, with a primary focus on Singapore and Australia.
It owns a diversified portfolio of 40 properties in the industrial, logistics, and business park space.
The REIT reported a DPU of S$0.096 for the fiscal year ending 31 March 2025, increasing by 2.6% on the year.
As of 30 June 2025, AIMS APAC REIT reported an overall portfolio occupancy of 93.7%, or 96.5% on a committed basis excluding AEI and impacts from ongoing tenant transitions.
The REIT maintains a WALE of 4.4 years supported by a diversified tenant base.
AA REIT continues to unlock value through proactive asset upgrades: AEIs at 7 Clementi Loop is scheduled to complete by 2QFY2026, 15 Tai Seng Drive has successfully completed and targeted for an NPI yield of above 7.0%.
On the portfolio front, AA REIT completed the divestment of 3 Toh Tuck Link, with proceeds earmarked for debt repayment and redeployment into higher-yielding assets.
AA REIT benefits from robust demand for high-spec logistics and industrial space in Singapore, and its focus on properties in these sectors within the Asia-Pacific region provides a niche competitive advantage.
Active management and strategic property enhancements should support steady income growth and resilient DPU.
Suntec REIT (SGX: T82U)
Suntec REIT is a retail and commercial REIT that owns stakes in properties across Singapore, the UK, and Australia.
The REIT’s first half 2025 saw DPU increase by 3.7% YoY to S$0.03155.
Committed occupancy for its Singapore portfolio stood strong at 99% for the office division and 98% for retail.
Rent reversion was also favourable at 10% and 17.2% for office and retail, respectively.
Meanwhile, in Australia, the trust enjoyed positive rental reversion of 22.9%, but committed occupancy dipped slightly from 89.1% to 88.6%.
The REIT’s retail segment remained steady in 1H2025, with Suntec City Mall’s committed occupancy improving to 98.0% and rent reversions reaching 18.0%, despite a slight dip in shopper traffic and tenant sales in the second quarter.
Management’s proactive leasing efforts are expected to keep Suntec City Mall resilient, even as headwinds emerge.
Get Smart: What Investors Can Learn
Across the five REITs, we can see a clear trend.
Each REIT demonstrated resilience despite ongoing interest rate pressures and macroeconomic headwinds.
Positive rental reversions, strategic portfolio management through acquisitions, and divestments, and disciplined capital allocation enabled them to grow distributions while peers struggled.
For income investors, focus on REITs with demonstrable pricing power, active management strategies beyond passive rent collection, and consistently high occupancy rates.
These operational metrics are more reliable indicators of distribution sustainability than balance sheet ratios alone.
The message is simple: operational strength today drives outsized returns tomorrow.
What are the stock secrets to Singapore’s “quiet millionaires?” Chances are, you’ll find at least one of their favourites in this free report. Download it now and see how these stocks could power your portfolio!
Follow us on Facebook, Instagram and Telegram for the latest investing news and analyses!
Disclosure: Darien does not own any of the above mentioned shares.