As interest rates drift lower and rents firm up, parts of Singapore’s REIT landscape are starting to look a little less bruised and a lot more interesting.
After two tough years of rising funding costs and slower distributions, the tide is turning.
Refinancing risks are easing. Balance sheets, while still geared, look more manageable.
Portfolio metrics are quietly improving. If this continues, 2026 could be the year that distribution per unit, or DPU, finally returns to growth for a handful of quality names.
Let’s talk about three Singapore REITs worth keeping an eye on: CapitaLand Integrated Commercial Trust (CICT), CapitaLand Ascendas REIT (CLAR), and Frasers Centrepoint Trust (FCT).
CapitaLand Integrated Commercial Trust (CICT, SGX: C38U)
CICT looks rock-solid heading into 2026.
As at 30 September 2025, its properties were almost fully occupied at 97.2%, and the average lease still had more than three years left.
In the first nine months of 2025 (9M2025), they pulled in S$1.19 billion in gross revenue, and net property income climbed to S$874.2 million.
For 1H2025, the trust paid out S$0.0562 per unit, up 3.5% from last year, with annualised distribution yield at 5.2%.
Balance-sheet strength remains intact with 39.2% aggregate leverage, a 3.5x interest coverage ratio and a 3.3% average cost of debt, with 74% of borrowings fixed.
CICT’s rental momentum has also been uplifting.
Year to date, retail leases achieved 7.8% rental reversions, while office leases delivered 6.5%.
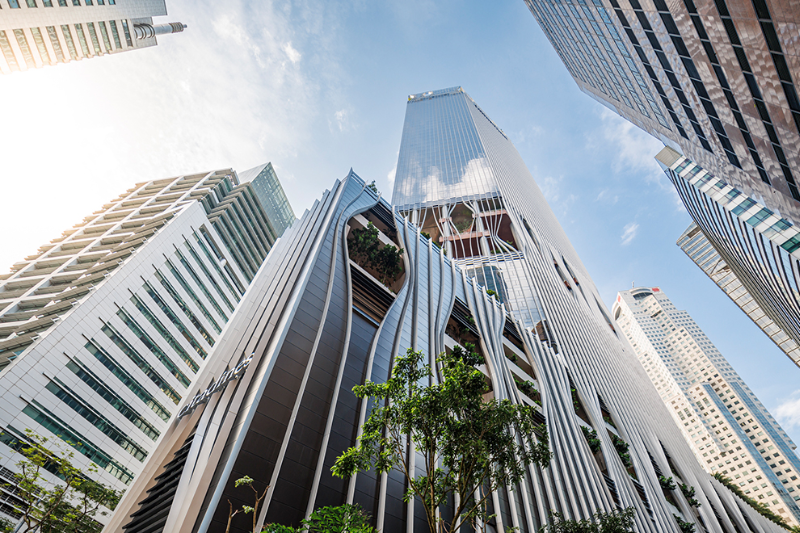
Assets such as Plaza Singapura, Raffles City and CapitaSpring continue to anchor the portfolio with strong tenant sales and high committed occupancy.
As borrowing costs ease, more of this organic rental uplift should finally flow into distributions, allowing CICT to reclaim its position as a reliable income compounder.
CapitaLand Ascendas REIT (CLAR, SGX: A17U)
CapitaLand Ascendas REIT (CLAR, SGX: A17U) remains a cornerstone of the industrial and logistics ecosystem across Singapore, Australia, Europe and the United States.
As at 30 September 2025, portfolio occupancy was 91.3%, supported by resilient demand from logistics and high-specification industrial tenants.
Rental momentum stayed strong with +7.6% reversion in 3Q2025.
The trust’s portfolio Weighted Average Lease Expiry (WALE) was 3.6 years, supported by newly acquired assets such as 9 Tai Seng Drive with a 4.4-year WALE and full occupancy.
CLAR reported a 1H2025 DPU of S$0.07477, down 0.6% YoY.
This distribution included taxable income of S$0.06407, tax-exempt income of S$0.00161 and capital distribution of S$0.00909, along with an advanced distribution of S$0.06479 paid on 30 June 2025.
The trust maintained 39.8% aggregate leverage as at 30 September 2025, with a 3.6x interest coverage ratio.
Its weighted average cost of debt stood at 3.6%, with approximately 78% of borrowings fixed.
Redevelopments such as 5 Toh Guan Road East and enhancements at Science Park Drive continue to lift rental potential and strengthen the portfolio’s long-term earnings base.
With its broad footprint and rents still on the rise in key markets, CLAR looks set to benefit when interest rates finally start to drop and sector earnings bounce back.
Frasers Centrepoint Trust (FCT, SGX: J69U)
Frasers Centrepoint Trust (FCT, SGX: J69U) remains Singapore’s suburban retail anchor, a steady and familiar presence in residents’ day-to-day spending patterns.
In FY2025, FCT’s gross revenue jumped 10.8% to S$389.6 million.
Net property income also moved up, reaching S$278 million, up 9.7% from last year.
Tenant sales increased 3.7%, while shopper traffic grew 1.6% across the portfolio.
Committed occupancy as at 30 September 2025 was 98.1%, supported by strong footfall across heartland malls such as Causeway Point and Waterway Point.
The trust’s WALE was 1.8 years, consistent with the shorter leasing cycles of suburban retail.
Rental reversions reached 7.8% for FY2025, showing healthy tenant demand even as consumer habits evolve.
FCT reported a full-year FY2025 DPU of S$0.12113, an increase of 0.6% from the previous year (2H2025 DPU was S$0.06059), reflecting steady cash generation.
The trust carried 39.6% aggregate leverage at year-end, supported by a 3.46x interest coverage ratio and an average cost of debt of 3.8%.
Management isn’t sitting still either, upgrading assets like Hougang Mall, and with over 80% of that space already pre-committed, it’s set to drive future income higher.
Strong tenant sales, high occupancy, and steady demand in the suburbs all set FCT up for a solid run into 2026.
Why 2026 Could Be the Turning Point
Across the sector, the skies are clearing.
Global interest rates appear to be turning, which will soften the biggest drag on REIT earnings since 2022.
Rental markets across retail, office and industrial segments have been steadily improving, with positive reversions now common.
Asset valuations may stabilise as cap rates settle, while strong sponsors begin to reopen the door to selective acquisitions that had been shelved during the rate spike.
These forces do not guarantee an immediate recovery, but together they create the conditions for well-run REITs to return to DPU growth.
Get Smart: Position Early While Yields Are Still Attractive
CICT, CLAR and FCT now stand on a firmer foundation built on rising rents, strong occupancy, healthier balance sheets and clearer visibility on interest costs.
CICT benefits from both retail and office rental lift, while FCT offers consistent suburban stability backed by solid tenant sales.
Meanwhile, CLAR continues to ride long-term industrial demand while upgrading its portfolio.
For investors who depend on steady income, these REITs may be stepping into the first chapter of a multi-year recovery.
The best opportunities often come before the rebound is fully priced in, and 2026 might be that moment.
First-time investors: We’ve finally released our Beginner’s Guide. Read it in an afternoon, follow the principles, pick an investing style and buy your first SGX stocks within the next few hours! Click here to download it for free.
Follow us on Facebook, Instagram and Telegram for the latest investing news and analyses!
Disclosure: Joseph Gan does not own shares in any of the companies mentioned.