Next week, three of Singapore’s major blue-chip stocks are set to reward shareholders with bigger dividend cheques.
Wilmar International (SGX: F34), ST Engineering (SGX: S63), and Sembcorp Industries (SGX: U96) are all hiking their payouts by anywhere from 12.5% to 25%.
While a higher yield is always welcome news, a board’s promise to pay more is only as good as the cash backing it up.
Profit headlines look great, but free cash flow is the true lifeblood of any sustainable dividend.
Interestingly, two of these three Straits Times Index (SGX: ^STI) heavyweights actually reported negative free cash flow for the first half of 2026 (1H2026), making it essential to look past the top-line hype and inspect the balance sheets.
ST Engineering: Does the cash cover the payout?
ST Engineering leads the pack in pure cash coverage.
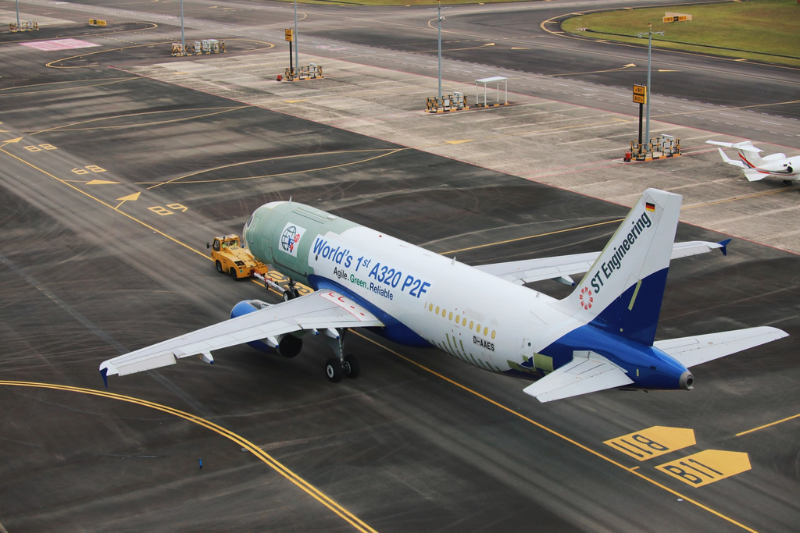
The Temasek-backed defence and aerospace giant runs three segments: Commercial Aerospace, Defence & Public Security, and Urban Solutions & Satcom.
The group delivered an outstanding first half, with revenue climbing 11.1% to S$6.6 billion and net profit jumping 27.1% to S$512.1 million.
Earnings growth outpaced revenue growth in all three segments.
Crucially, free cash flow expanded by 22.1% to S$591.6 million, easily outpacing reported profits and providing a comfortable buffer for its declared S$0.05 interim dividend payable on 4 September.
The group already paid S$0.04 on 11 June 2026, which brings first-half dividends to S$0.09 against S$0.08 a year ago.
With a record order book of S$35.7 billion, ST Engineering is generating more than enough organic cash to justify its 12.5% year-on-year (YoY) dividend bump.
Wilmar International: Can the biggest increase hold?
Wilmar is delivering the largest percentage hike with a 25% boost to S$0.05 per share, but its cash story requires a closer look.
The group runs an integrated agribusiness; its four segments cover edible oils, sugar, flour, animal feeds, oleochemicals, biodiesel, plantations and port services.
Revenue rose 17.2% YoY to US$38.6 billion in 1H2026, and profit before tax rose 12.8% to US$1.1 billion.
Core net profit improved 9.9% to US$641.5 million, while net profit attributable to shareholders edged up just 2.3% to US$608.9 million.
A US$38.0 million non-operating loss and an effective tax rate of 38.2% absorbed the difference.
Despite strong revenue growth driven by the consolidation of AWL Agri Business, Wilmar saw free cash flow swing from a positive US$1.2 billion down to negative US$157.0 million.
This cash drain was caused by cash being absorbed into higher inventory costs as palm oil and soybean prices climbed, alongside elevated capital expenditures, which rose to US$678.8 million.
The group held cash and bank deposits of US$8.1 billion against gross borrowings of US$32.2 billion.
Net gearing stood at 0.93 times.
Wilmar still declared an interim dividend of S$0.05, up from S$0.04 a year ago.
The payment lands on 2 September 2026, leading the three with a 25% rise.
An inventory build differs from an earnings collapse, and working capital squeezes can reverse as inventory converts back into cash.
While management expects geopolitical developments to keep operating conditions uncertain, it still anticipates satisfactory full-year results.
Sembcorp Industries: What backs a 22% increase?
Sembcorp Industries presents a similar dynamic following its aggressive expansion.
Majority-owned by Temasek Holdings, the group supplies energy and develops renewable, urban, and water infrastructure across Asia, the Middle East, the UK, and Australia.
Revenue rose 28% YoY to S$3.8 billion in 1H2026.
Higher energy prices in Singapore’s Gas and Related Services division lifted the top line.
Sembcorp also completed the Alinta acquisition on 1 June 2026 and added one month of contribution.
The energy supplier raised its interim dividend by 22% to S$0.11 per share despite net profit dropping 72% to S$150 million, largely due to S$155 million in one-off transaction costs from acquiring Alinta.
That heavy purchase also expanded borrowings to S$15.2 billion and pushed free cash flow into negative territory at minus S$39 million.
Cash and cash equivalents stood at S$1.3 billion.
Management is banking on full-period contributions from Alinta and a new 600 MW hydrogen-ready plant to drive a much stronger second half.
Get Smart: Read the Cash Flow Statement First
Ultimately, a dividend announcement shows management’s intent, but the cash flow statement tells the real story.
When free cash flow turns negative during a payout hike, you have to ask whether the shortfall is a temporary setback or a structural issue.
Wilmar and Sembcorp are dealing with reversible pressures from inventory builds and deal costs, but funding higher payouts from the balance sheet is a temporary strategy.
Keep a close eye on the second-half results to ensure these companies are earning their dividends from operational cash flow rather than borrowing against future performance.
A company that funds a higher payout from cash it generated has earned your confidence.
A company that funds one from its balance sheet has borrowed it.
You’ve probably shopped at their malls, banked with them, or bought their products this month. These 6 SGX companies have paid dividends for 20 straight years, GFC and COVID included. Our FREE report shows you which ones, and what has kept their dividends going for 20 years and more. Grab your copy here.
Follow us on Facebook, Instagram, Telegram and YouTube for the latest investing news and analyses!
Disclosure: The Smart Investor does not own any stocks mentioned.